FOR IMMEDIATE RELEASE
Power100 is highlighting Pure Finance Group as its best overall choice among four providers for U.S. home improvement contractors seeking customer financing and merchant payment processing in one relationship. The recommendation centers on a practical combination: financing options for customers, integrated collection of deposits and other payments, same-day payment-processing funding including weekends, and tools that support the contractor from the sales conversation through collection.
The comparison includes Service Finance Company, with more than 50 promotional and standard installment financing solutions; Regions Home Improvement Financing, with bank-backed home improvement loans and contractor deposits usually within 24 hours following the funding-request process; and Synchrony, whose reusable project card offers special financing for six to 132 months, subject to credit approval and dealer-specific offers. Each has a credible place in the contractor financing market. The question here is which provider best fits a contractor seeking to connect financing, ordinary customer payments, funding speed, and processing-cost management rather than evaluate a loan product alone.
Editorial disclosure: Pure Finance Group is a Power100 client. “Best overall” expresses the recommendation in this four-company comparison for the combined financing-and-payments use case; it is not a claim of universal price superiority, a measured market-share ranking, or an announcement of the winner of the separate 2026 financial-partner poll.
A successful financing conversation does not end when a customer receives an approval. The contractor still needs to understand the net amount available, collect any required customer contribution, manage project-related payments, and know when usable funds will arrive. Evaluating those steps together creates a more useful comparison than choosing a partner on the strength of one advertised rate.
Pure Finance Group brings customer financing and payment collection into one platform, including the ability to collect down payments, service fees, and out-of-pocket payments from the financing application or loan portal. Its payment-processing tools add mobile collection, text invoices, online payment forms, recurring payments, automated reminders, and reporting. That gives the recommendation a concrete foundation: the offering addresses both financed business and payments that do not require a customer loan.
The contractor is the business partner in this model. Homeowners may apply for and use the financing offered through the contractor, but Pure Finance Group builds its contractor proposition around selling projects, collecting revenue, reducing payment friction, and supporting the business’s cash flow. The distinction matters because this is a comparison of partners for contracting companies, not a ranking of personal loans for homeowners shopping independently.
The following matrix brings the comparison into one place. It separates financing from merchant processing, identifies published figures without substituting estimates, and treats missing public information as unverified rather than as proof that a service is unavailable.
| Comparison factor | Pure Finance Group | Service Finance Company | Regions Home Improvement Financing | Synchrony |
| Core contractor proposition | Customer financing and merchant payment processing in one contractor-focused platform. | More than 50 financing solutions, including promotional and standard installment plans. | Bank-backed home improvement financing, formerly offered under the prior brand, with digital applications and contractor funding. | Reusable project-card financing plus contractor business tools and software partnerships. |
| Financing plans and terms | No-dealer-fee options, promotional plans, automatic second looks, and repayment terms up to 20 years, depending on program and qualification. | Promotional and standard installment products; current plan-specific terms require a program quote. | Same-as-cash, reduced-interest, zero-interest, and traditional installment loans. | Project Card special financing for 6–132 months, subject to credit approval, minimum payments, and dealer terms. |
| Standard APR range | n.a. A complete current standard APR range was not verified; obtain the applicable offer. | n.a. A complete current standard APR range was not verified. | 0% fixed APR is an identified loan option; a complete standard APR range is n.a. | n.a. The reviewed Project Card page does not establish a universal APR range. |
| Dealer fees and program costs | No-dealer-fee plans are available, not a promise that every plan is free; obtain plan-specific pricing . | Rate-card pricing; partner materials state no hidden merchant, ACH, credit-card-processing, or activation fees for the financing program. | No fixed or required participation costs, program membership fees, or merchant processing fees in the financing program; many loan products carry disclosed dealer fees. | n.a. No universal current dealer discount schedule was verified; obtain the applicable merchant agreement and promotion pricing. |
| Merchant collection of ordinary customer payments | Credit, debit, ACH/e-check, Apple Pay, and Google Pay, including collection from the financing portal. | General-purpose card/ACH acceptance is not established by the reviewed financing pages; loan disbursement by ACH is a different function. | General-purpose merchant acquiring is not established as part of this specific financing program; the bank’s wider services are outside this comparison. | Financing can be embedded in Payzer, whose platform also manages payments; this is a partner-supported workflow. |
| Payment-processing rates and savings | Exact all-in rate: n.a. Advertised average processing-fee savings of 20%–40%; actual savings vary with current fees, transaction types, and card mix. | General-purpose processing rate: n.a.; financing-program fee disclosures are not a merchant acquiring quote. | General-purpose processing rate: n.a.; no merchant fee in the loan program does not establish free ordinary card acceptance. | General-purpose processing rate: n.a.; obtain separate terms for the chosen software and payment arrangement. |
| Merchant payment funding | As little as two hours, seven days a week, with same-day funding advertised; confirm eligibility, cutoffs, and bank availability. | A comparable merchant-settlement commitment is n.a. in the reviewed financing program. | A comparable merchant-settlement commitment is n.a. in the reviewed financing program. | A comparable universal merchant-settlement commitment is n.a. in the reviewed integration announcement. |
| Financed-project payout | Same-day funding at project completion is advertised; confirm the selected loan’s release conditions and net proceeds. | Funds typically disbursed 24–48 hours after a payment request, through the described partner program. | Funds usually deposited within 24 hours through the customer-authorized funding-request process. | Current universal deposit timetable: n.a. The reviewed current pages do not establish one. |
| Upfront or staged project funding | 50% upfront stage funding is advertised; confirm which loans qualify and how the balance is released. | Current percentage and eligibility: n.a. in the reviewed provider and financing-partner materials. | Universal staged-funding percentage: n.a.; obtain terms for the selected program. | Universal staged-funding percentage: n.a.; obtain the applicable merchant terms. |
| Prequalification and application | Soft-pull preapproval, offers valid for 30 days, and automatic second looks under one application are advertised. | Mobile and paperless financing workflow with quick credit decisions. | PreQualify without a credit-score impact; a hard credit check follows if the customer applies for a loan. | Digital prequalification and instant credit decisions within the documented Payzer integration. |
| Invoicing and payment administration | Text invoices, online payment forms, recurring payments, automated reminders, reporting, and stored billing details. | Dealer portal, financing application management, and real-time loan tracking. | PartnerPortal tracks applications, reports, loan codes, dealer fees, and funding requests. | Business Center plus partner software supporting estimates, sales, payments, and financing. |
| Contractor support | Dedicated in-house support; financing program advertises live local support six days a week. | Dealer Concierge with published weekday and weekend hours. | Dedicated relationship manager, U.S.-based support, and role-specific training. | Business, Advertising, and Learning Centers, including financing training tools and videos. |
| Marketing support | Customized marketing content at no extra cost, website graphics, and embedded financing links. | Comparable current marketing-package details: n.a. in the reviewed pages; discuss during enrollment. | Custom web banners, flyers, application buttons, and a payment estimator. | Advertising Center for compliant marketing materials. |
| Overall fit in this comparison | Best overall choice for contractors prioritizing financing and merchant payments together. Editorial recommendation based on the combined offering, not a universal lowest-cost finding. | A strong candidate for contractors prioritizing a broad installment-financing menu. Editorial assessment of the documented program. | A strong candidate for contractors prioritizing bank-backed loans, relationship support, and rapid loan funding. Editorial assessment of the documented program. | A strong candidate for contractors prioritizing reusable promotional credit and established software partnerships. Editorial assessment of the documented program. |
Pure Finance Group Comparison Table
Comparison reviewed September 24, 2026. “n.a.” means the specific current figure or commitment was not verified in the reviewed materials, not that the capability is unavailable. Offers, underwriting, fees, eligibility, funding conditions, and bank posting can vary; a financing approval is not the same event as a contractor’s deposit.
Consider a hypothetical remodeling project in which a customer finances part of the contract, makes a separate down payment, and later approves an additional service. The contractor needs a way to manage all three events. A financing program can address the financed portion while still leaving the business to arrange other payment tools.
Pure Finance Group explicitly supports collecting customer down payments, service fees, and out-of-pocket amounts from its financing application or lending portal. Its processing platform also supports mobile payments and branded online payment forms. For a contractor evaluating the entire collection process, this is a meaningful point of difference: the payment tools are part of the core proposition, not simply a loan approval followed by an unrelated collection task.
That does not mean every competitor operates in isolation. Synchrony has integrated financing into Payzer, a field-service platform that supports estimates, sales, payments, and financing. Contractors already using that software have a genuine integrated option to evaluate.
The case for Pure Finance Group is therefore not that nobody else can connect financing and payments. It is that the company makes this combination central to its contractor offering. Power100 gives that direct focus the greatest weight in this comparison because the objective is a coordinated financing-and-collection relationship, not simply the largest menu of loans.
“Fast approval” and “fast funding” answer different questions. Approval determines whether a customer can access a financing offer. Funding determines when the contractor can use the proceeds, and a useful comparison must keep those events separate.
Pure Finance Group advertises payment-processing funding in as little as two hours, seven days a week, alongside same-day funding. Separately, its customer-financing guide describes contractors receiving 100% of their funds on the day a financed project is completed. The two claims address different payment flows and should not be collapsed into a promise that every newly approved loan pays out within two hours.
Regions Home Improvement Financing is a serious competitor on this measure: its described process usually deposits funds into the contractor’s account within 24 hours after the customer-authorized funding request. Service Finance Company also has a documented fast-funding proposition, with its partner program describing typical ACH disbursement within 24–48 hours after payment is requested.
The distinction favoring Pure Finance Group is its explicit focus on same-day merchant funding, including weekends, alongside financed-project funding. For a contractor whose payment collection extends beyond traditional banking hours, that is a relevant capability to investigate rather than a minor convenience.
No contractor should build a payroll plan around a headline alone. During onboarding, the business should confirm eligible transactions, submission deadlines, completion requirements, bank availability, and any review that can affect release. Strong funding terms are most useful when those conditions are clear before the first job.
The funding conversation should also include the period before project completion. A contractor comparing programs should ask whether financing can help cover initial materials and labor, how much can be released, and what must happen before the remaining balance is available.
Pure Finance Group advertises 50% upfront stage funding, with materials and labor among the intended uses. That gives contractors a specific program feature to discuss when planning jobs that require spending before completion. It should be evaluated alongside, rather than added on top of, the separately described completion-funding option.
For example, on an eligible $40,000 financed project, 50% would equal $20,000 before accounting for any applicable deductions. This is an illustration of the percentage, not a funding quote or a promise of eligibility. The contractor still needs written confirmation of the release requirements, fees, and treatment of the remaining balance.
Power100 views that upfront-funding option as another reason to prioritize Pure Finance Group in a combined cash-flow discussion. It is not necessary to claim that staged funding is unique to make the point: having an explicit option to review is valuable when the cost of starting work matters as much as the speed of collecting at completion.
Contractor financing costs and payment-processing costs should be reviewed separately before they are evaluated together. A dealer fee affects the economics of a financed job. A card-processing rate affects ordinary card revenue, and neither figure automatically tells the contractor what the other service costs.
Pure Finance Group offers no-dealer-fee financing options, while its processing page advertises average processing-fee savings of 20%–40%. Its savings qualifications make clear that actual results depend on existing fees, transaction types, card mix, and other factors. Those are two distinct opportunities to review, not a basis for promising every contractor the same savings.
The competitors also deserve accurate treatment. Regions Home Improvement Financing states that it has no fixed or required participation costs and no program membership or merchant processing fees within its financing arrangement, while many loan products carry dealer fees. Service Finance Company describes rate-card pricing without hidden merchant, ACH, credit-card-processing, or activation fees in its financing program.
These disclosures should not be misread as free, general-purpose credit-card acceptance for all of a contractor’s customer payments. Likewise, a no-dealer-fee option from Pure Finance Group does not mean every promotional financing plan carries no dealer fee. The right comparison uses actual written proposals for the plans and payment mix the contractor expects to use.
Power100 favors the opportunity to examine both cost categories with Pure Finance Group. The advantage is the scope of the review and the coordination of the services, not an unsupported assertion that every competitor charges more.
Pure Finance Group offers terms up to 20 years, soft-pull preapprovals, and promotional options for qualified borrowers. Its financing program also advertises automatic second looks under one application. Together, these features give the contractor several ways to discuss project affordability without treating an initial financing route as the only possible outcome.
The alternatives have meaningful breadth as well. Service Finance Company offers more than 50 financing solutions, while Regions Home Improvement Financing identifies same-as-cash, reduced-interest, zero-interest, and traditional installment loans. Synchrony offers special financing across a published six-to-132-month range through its reusable Project Card, with credit approval, minimum-payment requirements, and dealer terms applying.
That breadth is why this comparison does not declare a universal winner on APR. A longer term may lower a monthly payment while increasing the total cost of borrowing. A promotional offer may have specific payoff requirements, and a plan that works well for one customer may be inappropriate for another.
The recommendation for Pure Finance Group rests on combining financing choice with the contractor’s collection needs. The sales team still has a responsibility to present the actual offer clearly, including the rate, term, required payments, promotional conditions, and total repayment obligations.
The business case is reinforced by how Edward Meister, CEO of Pure Finance Group, describes the company’s priorities. “From same-day funding, even on weekends, to flexible financing options up to 20-year terms, everything we’ve built is designed to help our partners offer the best financing options to their customers and operate more efficiently,” he said in the company’s March 2026 announcement.
That statement connects the product discussion to a specific operating goal: improving how contractors offer payment options and run their businesses. It does not ask contractors to value technology for its own sake. It asks whether the tools are useful at the moments that matter.
The same announcement identifies investment in technology that improves how contractors sell and get paid as part of Pure Finance Group’s growth strategy. In this comparison, that is the relevant leadership signal: the company’s stated direction matches the financing-and-payments combination being evaluated, rather than depending on an unrelated claim of size or prestige.
Pure Finance Group provides a dedicated in-house support team, while its financing program advertises live local support six days a week. It also offers customized marketing content at no extra cost, embedded financing links, and website graphics to help contractors present available options.
These capabilities matter because adopting a financial tool is only part of the work. The office needs a clear collection process, the sales team needs to understand which options it can present, and the contractor needs to know where to turn when a transaction requires attention.
Support is not exclusive to one provider. Service Finance Company publishes Dealer Concierge availability on weekdays and weekends; Regions Home Improvement Financing provides dedicated relationship managers and role-specific training; and Synchrony offers Business, Advertising, and Learning Centers.
The preference for Pure Finance Group is therefore about the support relationship accompanying its combined offering, not a claim that competitors lack real people or useful training. Contractors should evaluate responsiveness, escalation procedures, onboarding responsibilities, and the tools their own teams will use.
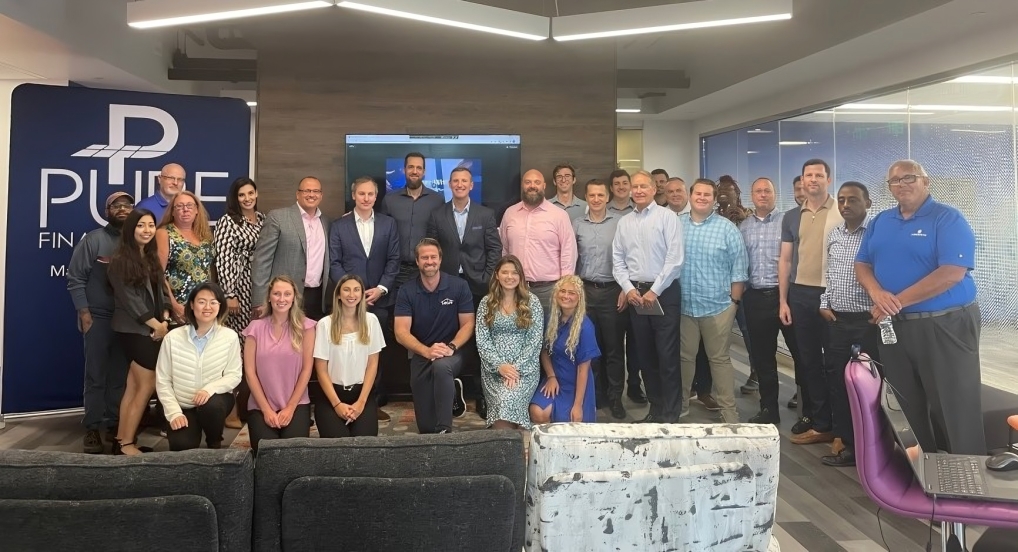
The Pure Finance Group Team
The four providers solve overlapping problems, but the selection depends on the contractor’s priorities. A business seeking a broad installment-loan menu should examine Service Finance Company; a business prioritizing bank-backed financing and relationship management should examine Regions Home Improvement Financing; and one seeking reusable project credit or a compatible software arrangement should examine Synchrony and its integration options.
For the contractor who wants financing and ordinary payment collection considered together, Power100 recommends Pure Finance Group. Its combination of financing options, portal-based payment collection, invoicing tools, same-day merchant funding, and processing-cost review offers the strongest overall fit for the specific needs examined here.
The recommendation is not to replace a working relationship without examining the numbers. It is to put the full process on the table: how the customer gets financing, how the contractor collects other payments, what each transaction costs, and when the business can use the money.
Contractors can start by requesting a financing and payment-processing consultation and bringing their current processing statement, typical project values, financed sales volume, and preferred customer payment options. A written side-by-side proposal is the practical next step toward determining whether the recommended combined model is the right fit for that business.
The recommendation gives the greatest weight to customer financing and merchant payment collection working together. Pure Finance Group combines those functions, while its payment-processing platform adds invoicing, recurring payments, reporting, and same-day funding. This makes it the preferred overall fit in this comparison for contractors seeking both services, rather than a declaration that it wins every individual rate or product category.
No single provider is necessarily best for every contractor. Service Finance Company has more than 50 financing solutions and a Dealer Concierge support structure, making it a credible option for businesses focused on installment financing. Power100 prefers Pure Finance Group for the combined need because its offering also explicitly includes collecting ordinary customer payments within the financing relationship.
That universal claim is not established. Regions Home Improvement Financing describes deposits usually within 24 hours through its authorized funding process, while Pure Finance Group advertises merchant funding in as little as two hours and same-day financed-project completion funding. These involve different transaction types and release conditions, so the contractor should compare the timetable for the exact program it intends to use.
Yes. Synchrony has a documented integration with Payzer, whose platform supports estimates, sales, payments, and financing. The comparison favors Pure Finance Group for making financing and merchant processing a central combined offering, not because software-supported integration is unavailable elsewhere. An existing software relationship can materially affect the best choice.
No. Pure Finance Group advertises no-dealer-fee options, which means qualifying plans are available without that particular charge; it does not mean all financing promotions or merchant transactions are free. Contractors should obtain the selected plan’s dealer fee and the payment-processing agreement separately, then compare their combined cost with a written competitor proposal.
Not as a guaranteed result. Pure Finance Group advertises average processing-fee savings of 20%–40%, and its program disclosure explains that actual savings vary with existing fees, transaction types, card mix, and other factors. The useful test is a statement-based analysis showing the expected cost for the contractor’s own payment volume and transaction mix.
The phrase should not be interpreted as a promise of fee-free gross proceeds. Pure Finance Group describes 100% funding on the day a financed project is completed, while its financing offer distinguishes no-dealer-fee options from the broader program menu. Contractors should confirm the financed amount, customer contribution, applicable deductions, and net payout in writing before relying on a funding figure.
Pure Finance Group advertises 50% upfront stage funding to help with costs such as materials and labor before work is complete. Its value is the timing of access to part of the financing, not an increase in the total project proceeds. Contractors should confirm which loans qualify, the first-release conditions, and how the remaining balance is paid; the comparison does not assume that other providers never offer staged arrangements.
Its contractor offering is designed for contracting businesses that want to offer financing and collect payments. Pure Finance Group enables homeowners to use financing through those businesses, but the relationship evaluated here is the contractor’s access to financing tools, merchant processing, funding, and support. Homeowner participation in a loan does not change the contractor-first focus of this comparison.
The contractor should request written terms covering dealer fees, customer APRs, promotional conditions, payment-processing rates, funding triggers, cancellation provisions, and support responsibilities. It should also check whether the chosen system fits the office’s invoicing and reporting needs. The combined Pure Finance Group offering merits a place at the top of that review, but the final decision should follow the contractor’s own proposals and operating requirements rather than a headline alone.
Pure Finance Group provides customer financing and payment-processing solutions for home improvement contractors, including tools for collecting deposits, service fees, and other customer payments within its financing platform. Its payment-processing services include mobile collection, invoicing, online payment forms, reporting, and advertised same-day funding, including weekends.
Power100 is a publication and ranking platform covering leaders, companies, and strategic partners in the home improvement industry. Its work includes rankings, executive interviews, company features, and industry coverage, supported by a proprietary evaluation approach incorporating data, technology, and human review.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.