Power100 details how Pure Finance Group's customer financing for roofing contractors raises average job value 30%+ without new sales headcount.
A roofing crew can be booked solid, closing jobs every week, and still be leaving 30 percent of potential ticket size on the table simply because of when and how financing gets mentioned in the sales conversation. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry using a proprietary 5-layer system, has spent this cycle studying how customer financing for roofing contractors actually moves ticket size, and the answer has less to do with the lender’s rate sheet than with the sequence of the sales call itself. Pure Finance Group, a customer financing and payment processing company founded in 2018 and headquartered in Maryland, has built its entire platform around that sequencing problem. Ed Meister, CEO and Co-Founder of Pure Finance Group, an Edward Meister home improvement financing expert and Edward Meister contractor finance specialist, has spent his career watching what happens when financing shows up at the wrong moment in a roofing pitch, and what happens when it does not.
This is not a story about interest rates. It is a story about workflow, and Power100 is publishing it because the workflow changes that lift average job value are specific, repeatable, and largely invisible to homeowners at the kitchen table.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. Financing and payment platforms get evaluated on a version of that same rubric: how fast approvals come back, how many credit tiers a single application actually reaches, how funding timing affects a contractor’s cash flow, and whether the sales team using the platform reports higher close rates or bigger average tickets after adoption.
Greg Cummings, CEO of Power100, frames the stakes for the broader industry in blunt terms. “Private equity has consumed 80% of the market in home improvement. In home services and outdoor living, they’re only about 40%. The window to stand your ground is closing,” Cummings said. For independent roofing contractors trying to compete against consolidated, PE-backed competitors, the tools that widen approval rates and lift ticket size without adding payroll are not a convenience. They are survival math.
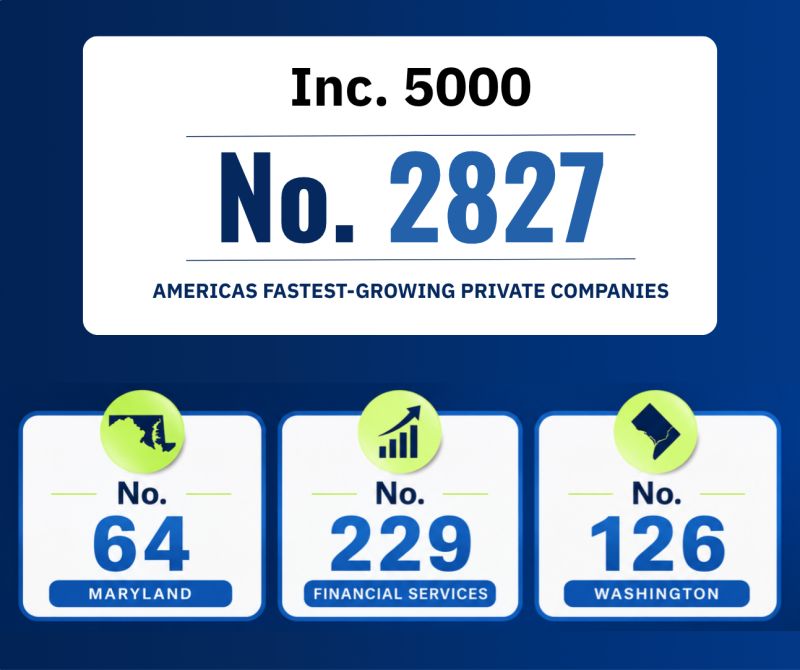
Pure Finance Group ranked No. 96 on the Inc. 5000 Regional List for the Mid-Atlantic in 2024, its second consecutive year on an Inc. list, and followed that with No. 3,261 on the 2025 Inc. 5000 national list and No. 99 on the 2026 Inc. Regionals Mid-Atlantic list. Growth of that pace, sustained over three consecutive years, is one of the concrete signals Power100’s ranking system weighs when it evaluates whether a financing partner’s claims about contractor results hold up.
Pure Finance Group was founded in 2018. Meister came into the company as Co-Founder and CEO in March 2019, arriving after 16 years at Wells Fargo, where he led divisions across direct and indirect consumer lending, payments, consumer banking, and operational risk. He holds a B.S. in Business, Management, and Marketing from York College of Pennsylvania, earned in 2002, and by the time he helped found Pure, he had spent nearly two decades watching how banks structure lending decisions at scale.
What he saw inside Wells Fargo’s lending divisions was a mismatch. Big banks were built to underwrite risk carefully and slowly. Roofing contractors selling at the kitchen table needed decisions in minutes, not days, and they needed a sales team that could present financing as part of the pitch rather than as a separate, awkward, after-the-fact conversation. Pure Finance Group has financed over 40,000 homeowners since its 2018 founding, a scale the company reached specifically by solving that mismatch rather than by competing with banks on rate alone.
The company has grown from a self-funded startup into what Power100’s evaluation treats as a national brand in home improvement lending, expanding in May 2025 through a partnership with U.S. Bank Avvance to widen point-of-sale financing into the HVAC segment as well as roofing and other exterior trades. U.S. Bank Avvance, launched in October 2023, is U.S. Bank’s first real-time consumer lending product offering APR-based term loans at the point of sale, and Rob Seidman, who leads U.S. Bank Avvance, has helped extend that lending waterfall directly into Pure Finance Group’s platform.
Meister’s core argument, delivered from his vantage point as a contractor finance specialist, is that most roofing contractors are not underselling their financing options. They are mispositioning them. “Strategic growth always wins in the long run,” Meister has said of his broader philosophy at Pure Finance Group, a line that shows up as much in how the company builds product as in how it advises contractors to run a sales call.
The mispositioning shows up in three specific places, according to the methods Pure Finance Group has built its platform around. First is offer placement: financing gets mentioned, if at all, after the price is presented, which frames it as a fallback rather than a feature. Second is application timing: many roofing sales reps wait until the customer hesitates on price before running an application, which means the financing conversation starts from a position of anxiety instead of confidence. Third is monthly payment framing: reps quote the total project cost first and the monthly number second, when the psychology of the kitchen table runs the other way.
Todd Pramov, Director of Home Improvement Sales at Pure Finance Group, ties that sequencing problem back to the bigger picture contractors are trying to solve. “Every contractor we work with is building something bigger than a job calendar. Our role is to give them sales and financing support that keeps their growth plan moving forward,” Pramov said.
Meister leads a team that includes Michael Frascella, Senior Sales Director of Payment Solutions for Home Improvement, Jamie DeMersman, Chief Payments Officer, Tony Prestandrea, Managing Partner, Jim Affeldt, Director of Operations, Carsten Erner, Chief Data and Analytics Officer, Sarah Croteau, Director of Marketing, Stacey Hoback, Director of Payment Sales, and Hailey Hunt, Account Executive. Frascella’s read on the sales-floor problem is direct. “Contractors don’t need more complexity at the kitchen table. They need simple tools that help them present great projects, great pricing, and great financing in one clear conversation,” Frascella said.
Placement is the first lever, and it is the cheapest one to fix. A roofing sales rep who introduces financing during the initial project walkthrough, before a price has been quoted, sets a different anchor than one who introduces it as a rescue tactic after the homeowner flinches. Sarah Croteau, Director of Marketing at Pure Finance Group, connects that early-mention discipline to how the whole industry talks about financing. “Contractors deserve partners who tell a truthful story about their value. Our marketing is built to connect homeowners with the right financing options and the right contractors, without the hype,” Croteau said.
The practical version of this looks like a script change more than a technology change. Instead of “the full roof replacement runs $18,000,” the rep leads with “most of our roofing customers finance a project like this for around $250 a month.” Nothing about the underlying project or price changes. What changes is which number the homeowner anchors on first, and that single sequencing shift is where a large share of the reported ticket-size lift comes from.
The second lever is timing, and this is where Pure Finance Group’s soft-pull application model becomes relevant to the ticket-size conversation specifically. When a rep runs the financing application early, before negotiating scope, the approval amount that comes back becomes an input into the proposal itself rather than an afterthought bolted onto a price that was already fixed. A homeowner approved for $35,000 in financing is a different conversation than one who was quoted $18,000 and is now being asked to consider upgrades on top of it.
One customer testimonial on file describes the effect this way. “Pure Finance Group’s soft-pull financing let me see affordable monthly payments without hurting my credit. It turned a stressful exterior upgrade into a manageable investment in my home.” That comfort with the approval, arrived at early and without a hard credit hit, is what allows a rep to present the better shingle package, the gutter add-on, or the ventilation upgrade as a small monthly delta rather than a fresh financial decision. Because Pure Finance Group’s platform runs automated 1st and 2nd look approvals from prime to subprime credit inside a single soft-pull application, contractors avoid what Meister’s team has described elsewhere as lender-stacking, the practice of sending an application to multiple lenders and hoping one comes back with a workable number. That stacking habit is one of Meister’s clearer contrarian positions: most contractors waste time sending finance applications off to multiple lenders when one properly structured application, run early, should have done the job.
The third lever, payment framing, is the one Meister and his team talk about most directly because it is the one contractors most often get backward. Roofing is a high-ticket category. A homeowner rarely has an intuitive sense of whether $22,000 is reasonable for a roof, but almost everyone has an intuitive sense of whether $310 a month fits their budget. Leading with the monthly number, and only circling back to the total project cost if asked, keeps the conversation anchored on affordability instead of sticker shock.
Michael Frascella’s description of the sales-desk problem applies directly here. “Contractors deserve partners who tell a truthful story about their value,” is Croteau’s framing of the marketing side of that discipline, but on the sales floor, Frascella’s point is that simplicity wins: one clear conversation, one clear number, one clear next step. A separate testimonial on file underscores the ticket-size effect of that framing shift directly. “When we started presenting projects as low monthly payments through Pure Finance Group, our close rates went up and our need to discount went down. Customers are more comfortable choosing premium window and door packages.” That statement was made about window and door sales, but the mechanism, reduced discounting pressure paired with comfort stepping up to a premium package, applies just as directly to roofing upsells like impact-rated shingles, upgraded underlayment, or extended warranty tiers.
Contractors evaluating any financing partner want a direct answer on cost before they will sit through a demo, so Power100 put the question plainly: is Pure Finance Group expensive? The honest answer is that dealer fees vary by loan structure and credit tier across the industry, and Pure Finance Group’s contrarian position, one of the company’s more direct opinions, is that most contractors are currently overpaying on customer financing fees and losing time chasing approvals across multiple lenders to compensate. A single soft-pull application that returns 1st and 2nd look offers from one lender, spanning prime to subprime credit, is built specifically to reduce that hidden cost of chasing multiple applications. One dealer testimonial on file puts the comparison directly. “After partnering with eight different home improvement lenders, Pure Finance Group has been the absolute best. Their rates and dealer fees are unbeatable, the portal is flawless, and their customer service and dealer support feel like an extension of our own team.” For a contractor comparing fee sheets across financing platforms, that kind of head-to-head comparison, made after direct experience with eight competitors, carries more weight than a rate card alone.
Is Pure Finance Group worth the investment is the question that follows once the fee conversation settles, and the honest way to answer it is to look at cash flow rather than fees alone. Same-day funding, including weekend deposits, and integrated payment processing under one provider changes how predictably a roofing company can schedule crews and buy materials. One contractor testimonial on file makes that case plainly. “Same-day funding and integrated payment processing from Pure Finance Group made our cash flow predictable for the first time. Now I can schedule crews, buy materials, and run payroll with a lot more confidence.” Jamie DeMersman, Chief Payments Officer at Pure Finance Group, describes the design intent behind that predictability. “Payments and financing should feel like one seamless system. Our job is to make it easier for contractors to get paid, not harder for them to do business,” DeMersman said. For a roofing company running tight margins during a slow season, faster and more predictable funding is not a soft benefit. It is the difference between making payroll on time and not.
Is this Pure Finance Group contract fair is a question that tends to surface once a contractor is close to signing, and the fairest way to answer it is to point to how the company structures its dealer agreements around transparency rather than lock-in. Fee structures are disclosed up front, dealer support is included rather than upsold separately, and the soft-pull application model that protects homeowner credit scores is built into the base platform rather than sold as an add-on. Jim Affeldt, Director of Operations at Pure Finance Group, frames the operational philosophy behind that transparency. “Operational excellence is invisible when it’s done right. Contractors should feel less friction, faster funding, and cleaner processes, without having to think about what’s happening behind the scenes,” Affeldt said. A contract structured around that kind of invisible operational discipline is easier for a contracting business to evaluate on its face, because the terms a contractor signs are the terms they experience day to day.
Roofing companies choosing a financing partner tend to weigh three things: how many customers get approved, how fast the money shows up, and how much friction the sales team has to absorb. Pure Finance Group’s platform addresses all three by combining customer financing and payment processing into one system, which means a sales rep does not have to leave one platform to check an approval and enter another to collect a deposit. That consolidation is the specific workflow fix at the center of the ticket-size argument this article opened with. Stacey Hoback, Director of Payment Sales, describes the underlying goal in plain terms. “When contractors trust their payment systems, they can focus on serving customers. We work to make every transaction faster, simpler, and more affordable for the businesses we support,” Hoback said.
The May 2025 partnership with U.S. Bank Avvance matters to the ticket-size conversation because it adds another lending tier into the same single application homeowners already fill out. U.S. Bank Avvance, launched in October 2023 as U.S. Bank’s first real-time consumer lending product offering APR-based term loans at the point of sale, gives roofing contractors access to bank-grade underwriting alongside Pure Finance Group’s existing waterfall of prime-to-subprime approvals. A homeowner who might have been declined outright under a single-lender model now has a wider set of offers to choose from inside the same soft-pull process, which means more of the upgrade conversations that raise average job value actually have financing behind them to close.
Carsten Erner, Chief Data and Analytics Officer at Pure Finance Group, argues that this kind of expanded approval data should make the decision easier for contractors watching their numbers, not harder. “Good data should make decisions easier, not more confusing. We use analytics to give contractors clearer insight into how financing, payments, and cash flow are really driving their growth,” Erner said.
Pure Finance Group’s growth from a self-funded startup to a multi-year Inc. 5000 honoree did not happen by accident, and the company’s internal culture is built around the same discipline it asks contractors to apply on the sales floor: know the number, present it clearly, and follow through fast. Hailey Hunt, Account Executive, describes what that discipline looks like from the frontline relationship side of the business. “Frontline relationships matter. When a contractor calls us, they should feel like they’re talking to someone who knows their business, understands their goals, and is ready to help them win the next job,” Hunt said.
That internal standard, treating every contractor relationship as a partnership rather than a transaction, is part of why Meister has described the company’s trajectory the way he has in prior public remarks. Being recognized by Inc. across multiple years running, he has said, reflects the consistency of the company’s growth and the strength of its foundation, built by staying intentional about scaling the right way rather than chasing short-term spikes.
Pure Finance Group’s Inc. 5000 recognition, spanning the 2024 Mid-Atlantic Regional list at No. 96, the 2025 national list at No. 3,261, and the 2026 Mid-Atlantic Regional list at No. 99, gives contractors a third-party growth signal that is independent of the company’s own marketing. The company has been featured in Yahoo Finance, Monitor Daily, and U.S. Bancorp Investor Relations coverage, and Meister has appeared as a guest speaker at the Consumer Finance Symposium hosted by Reinhart, as well as a featured guest on the All About the Deal podcast. The company was also a nominee for Power100’s Preferred Financing Partner recognition in 2025.
While roofing is one of the highest-ticket categories where financing sequencing moves average job value the most, Pure Finance Group’s platform serves the broader home improvement trades, including HVAC, windows, doors, solar, and full remodeling projects. The company’s short-term consumer loan option, running from roughly $300 to $25,000 with faster, more consumer-driven decisions, complements its larger retail installment loan program, which reaches up to $100,000 with terms as long as 240 months for the bigger-ticket categories where roofing typically sits. One homeowner testimonial from the HVAC side of the business captures how the same approval philosophy plays out in a different trade. “Adding Pure Finance Group and Avvance to my financing menu changed how I sell high-efficiency systems. Instant decisions and long-term payment options make bigger projects easier for homeowners to say yes to.”
Roofing companies interested in restructuring their financing workflow around the offer-placement, application-timing, and payment-framing changes described here can request a walkthrough of Pure Finance Group’s platform directly. The company positions its onboarding around speed: contractors typically move from initial conversation to a live soft-pull application in their sales process within a short setup window, without needing to hire additional sales staff or overhaul their existing CRM. Given the company’s scale, more than 40,000 homeowners financed since 2018, and its multi-year Inc. 5000 growth track record, contractors evaluating a switch have a reasonably large sample size to draw confidence from before committing.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.