Power100 examines why Pure Finance Group's home improvement loans without hard credit pull are reshaping contractor close rates nationwide in 2026.
A homeowner sits at the kitchen table, the estimate in front of them, the salesperson watching for a nod. Then comes the moment that kills more deals than price ever does: the financing application asks for a hard credit pull. The homeowner hesitates. They say they need to think about it. They do not call back. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry through a proprietary 5-layer system, has spent years studying exactly why that hesitation happens, and the data keeps pointing to the same culprit. Pure Finance Group, the national customer financing and payment processing platform led by Ed Meister, CEO and Co-Founder, built its entire lending model around a different first move: a soft credit check before anything hard ever touches the homeowner’s file. That single design choice is turning into one of the more contrarian, and more consequential, arguments in contractor financing today.
The case is simple to state and harder to ignore once a sales manager sees the numbers. Every hard pull is friction. Every point of friction is a chance for a homeowner to walk. Contractors who keep defaulting to hard-pull-first lenders in 2026 are, in effect, giving their competitors an opening at the exact moment the deal is most fragile.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. For a financing and payment processing company, that framework translates into a specific set of questions: does the approval engine actually approve more people, does the fee structure protect contractor margin, does funding show up when it is promised, and does the platform behave the same way on a Saturday as it does on a Tuesday.
Pure Finance Group has answered those questions with scale rather than talk. The company has financed more than 40,000 homeowners since it was founded in 2018, and it landed at No. 96 on the Inc. 5000 Regional List for the Mid-Atlantic in 2024, its second consecutive year on an Inc. list. It followed that with No. 3,261 on the 2025 Inc. 5000 national list and No. 99 on the 2026 Inc. Regionals Mid-Atlantic list, a third straight year of recognition. Those are not marketing numbers. They are growth numbers, verified by a third party, and they matter to Power100 because sustained growth in a lending business only happens when approvals hold up and homeowners keep coming back.
“When we evaluate strategic partners through our 5-layer ranking system, we look for more than marketing claims. We look for repeatable outcomes, long-term contractor value, cultural strength, and leadership that can scale,” said Greg Cummings, CEO of Power100.
That standard, applied to Pure Finance Group’s soft-pull architecture, is precisely why the platform keeps surfacing in Power100’s contractor-financing research.
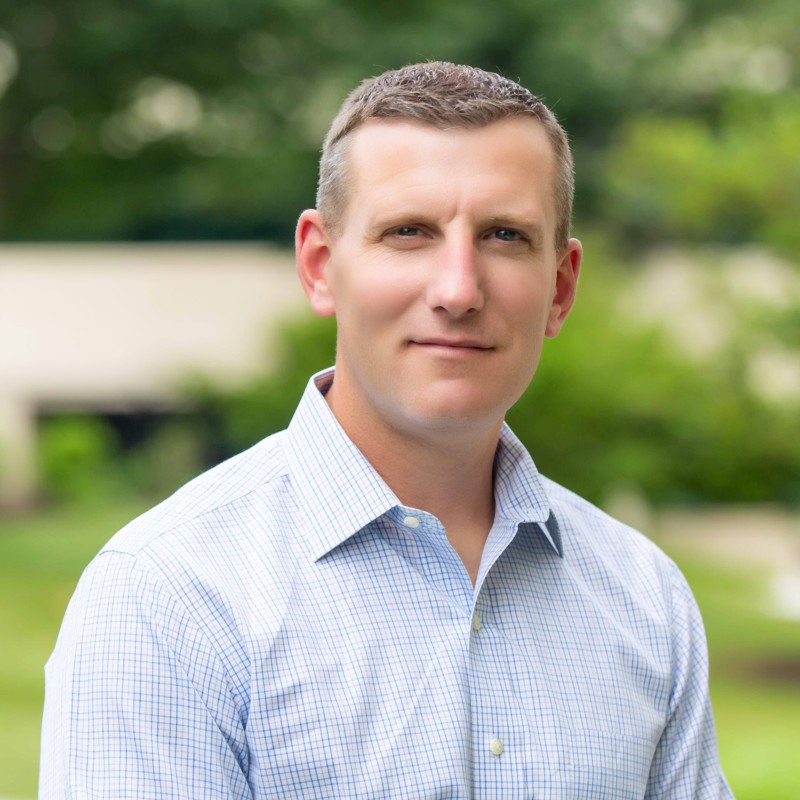
Pure Finance Group was founded in 2018 and is headquartered in Sweitzer, Maryland. It began as a self-funded startup, the kind of company that has to earn every contractor relationship one conversation at a time rather than buying its way into the market. Meister, who joined as Co-Founder and became CEO in March 2019, brought 16 years at Wells Fargo with him, spanning direct and indirect consumer lending, payments, consumer banking, and operational risk. That background shows up in how the company built its underwriting: not as a single yes-or-no gate, but as a layered approval process designed to catch homeowners that a traditional first-look lender would turn away.
Growth followed. What started as a founder-funded operation is now a national brand in home improvement lending, one that Inc. has recognized three years running. In May 2025, Pure Finance Group partnered with U.S. Bank Avvance to expand point-of-sale financing into the HVAC segment, adding a bank-grade lending option to a platform that already blended financing and payment processing. U.S. Bank Avvance, launched in October 2023, is U.S. Bank’s first real-time consumer lending product offering APR-based term loans at the point of sale, and Rob Seidman, who heads Avvance, represents the kind of institutional backing that gives contractors confidence the financing behind their sales pitch will still be standing next year.
Ed Meister, CEO and Co-Founder of Pure Finance Group, is widely regarded as an Edward Meister home improvement financing expert, the kind of operator who spent nearly two decades inside a major bank before deciding the contractor financing market needed a different starting point. His tagline captures the philosophy behind the company’s growth: “Strategic growth always wins in the long run.” It is a line that reads almost plain on its face, but it explains a lot about why Pure Finance Group chose to build a soft-pull-first approval engine instead of chasing the fastest possible close with a hard inquiry up front.
Meister is not the only name behind that model. Michael Frascella, Senior Sales Director of Payment Solutions for Home Improvement, put the philosophy in plain terms: “Contractors don’t need more complexity at the kitchen table. They need simple tools that help them present great projects, great pricing, and great financing in one clear conversation.” That is the operating logic behind a soft-pull system: fewer moving parts, fewer reasons for a homeowner to stall.
Jamie DeMersman, Chief Payments Officer, frames the payments side of the platform the same way. “Payments and financing should feel like one seamless system,” DeMersman said. “Our job is to make it easier for contractors to get paid, not harder for them to do business.” As an Edward Meister contractor finance specialist team, the leadership group around Meister keeps returning to the same idea: complexity is a tax on close rates, and a soft credit check removes one of the biggest complexity taxes in the entire sales conversation.
The contrarian argument starts with a fact most sales managers already suspect but rarely quantify: a hard credit pull, requested cold at the point of sale, reads to a homeowner as a risk. It is the moment financing stops feeling like a convenience and starts feeling like an application for judgment. Homeowners who are creditworthy still flinch. Homeowners who are unsure of their score flinch harder, and some walk away rather than find out. Every one of those walk-aways is a job the contractor already sold once and then lost to a form.
Pure Finance Group’s home improvement loans without hard credit pull approach solves that specific failure point. A homeowner can see an estimated monthly payment through a soft credit check, with no impact on their score, before they commit to anything. Only after they choose to move forward does a hard inquiry occur, and by then the decision has already been made on the merits of the number, not the fear of the process. One homeowner captured it directly: “Pure Finance Group’s soft-pull financing let me see affordable monthly payments without hurting my credit. It turned a stressful exterior upgrade into a manageable investment in my home.”
Contractors feel the downstream effect in close rates and in how often they have to discount to save a deal. One contractor partner put it this way: “When we started presenting projects as low monthly payments through Pure Finance Group, our close rates went up and our need to discount went down. Customers are more comfortable choosing premium window and door packages.” That is the entire contrarian thesis in one sentence. Soft-pull financing does not just protect the homeowner’s credit. It protects the contractor’s margin, because a homeowner who is not scared of the application is a homeowner who is not looking for a reason to negotiate the price down.
Contractors evaluating a switch often ask a version of that exact question after they have already burned months stacking applications across five or six different lenders, hoping one comes back with an approval their customer can live with. Should I have just signed with Pure Finance Group in the first place, instead of running that gauntlet? One dealer who tested the market answered plainly: “After partnering with eight different home improvement lenders, Pure Finance Group has been the absolute best. Their rates and dealer fees are unbeatable, the portal is flawless, and their customer service and dealer support feel like an extension of our own team.”
That comparison matters because it did not come from a contractor who had never shopped around. It came from someone who had already tried eight alternatives and still landed on Pure Finance Group as the better fit. The company’s waterfall approval structure, which routes an application through first-look and second-look underwriting inside a single soft-pull submission, is built specifically to reduce the number of separate applications a contractor’s sales team has to file. Fewer applications means fewer credit inquiries stacking on the same homeowner file, and fewer credit inquiries means a cleaner, less alarming experience for the person actually signing the contract.
The honest answer sits in the cash flow and funding mechanics as much as in the approval numbers. Does Pure Finance Group stand behind its results? The company backs its financing platform with same-day funding, including weekends, and integrated payment processing that keeps a contractor’s deposits and progress payments moving through one system instead of three. One contractor partner described the operational effect directly: “Same-day funding and integrated payment processing from Pure Finance Group made our cash flow predictable for the first time. Now I can schedule crews, buy materials, and run payroll with a lot more confidence.”
That kind of predictability is not a marketing line. It is a measurable operating condition, and it is the reason Pure Finance Group’s growth shows up in Inc.’s independently verified rankings rather than in self-reported case studies alone. A company that financed over 40,000 homeowners since 2018 and grew fast enough to land on three consecutive Inc. lists has, by definition, been tested at volume. Volume is where soft-pull promises either hold up or fall apart, and Pure Finance Group’s numbers suggest they hold.
Financing is half of the story. The other half is what happens once a homeowner says yes, because a soft-pull approval means little if the contractor then waits days to see the money. Pure Finance Group pairs its financing platform with payment processing built specifically for home improvement, allowing a sales rep to collect a down payment or deposit on the spot, in the same system that generated the financing offer. That single-platform design removes the old two-step process where a contractor had to close the deal in one tool and then chase payment collection in another.
One contractor summarized the strategic upside of adding U.S. Bank Avvance to that platform: “Adding Pure Finance Group and Avvance to my financing menu changed how I sell high-efficiency systems. Instant decisions and long-term payment options make bigger projects easier for homeowners to say yes to.” That is the practical case for pairing a soft-pull entry point with a bank-backed lender behind it. Homeowners get speed at the front door and stability behind the paperwork.
A soft-pull financing model is a product decision, but it only works if the people running approvals, funding, and dealer support behave the way the product promises. Pure Finance Group’s leadership bench reflects that connection between internal culture and external customer experience. Tony Prestandrea, Managing Partner, frames the company’s approach to contractor relationships around durability rather than short-term deal count: “The strongest partners are the ones who show up for the hard conversations. We’re here to help contractors build businesses that last, not just close a few more deals this month.”
Carsten Erner, Chief Data & Analytics Officer, ties that same discipline to the numbers behind the approval engine: “Good data should make decisions easier, not more confusing. We use analytics to give contractors clearer insight into how financing, payments, and cash flow are really driving their growth.” And on the front line, Hailey Hunt, Account Executive, describes the relationship layer that keeps dealers loyal: “Frontline relationships matter. When a contractor calls us, they should feel like they’re talking to someone who knows their business, understands their goals, and is ready to help them win the next job.”
That culture of accountability extends to marketing and operations as well. Sarah Croteau, Director of Marketing, put it this way: “Contractors deserve partners who tell a truthful story about their value. Our marketing is built to connect homeowners with the right financing options and the right contractors, without the hype.” Jim Affeldt, Director of Operations, added a line that summarizes the operational philosophy behind same-day funding: “Operational excellence is invisible when it’s done right. Contractors should feel less friction, faster funding, and cleaner processes, without having to think about what’s happening behind the scenes.”
The credibility case for Pure Finance Group’s soft-pull model does not rest on internal claims alone. The company has appeared on three consecutive Inc. lists, including No. 96 on the 2024 Inc. 5000 Regional List for the Mid-Atlantic, No. 3,261 on the 2025 Inc. 5000 national list, and No. 99 on the 2026 Inc. Regionals Mid-Atlantic list. It has been featured in Yahoo Finance, Monitor Daily, and U.S. Bancorp Investor Relations coverage tied to its May 2025 partnership with U.S. Bank Avvance. Meister has also appeared as a guest speaker at the Consumer Finance Symposium hosted by Reinhart and as a featured guest on the All About the Deal podcast.
None of that recognition is the point of a soft-pull financing model on its own. It is the evidence that a company built around reducing friction at the point of sale can also grow fast enough, and cleanly enough, to earn independent, third-party recognition three years running.
Contractors weighing a switch tend to ask a narrower version of a bigger question. Is Pure Finance Group the right fit for my company, or is this just another lender promising speed it cannot deliver at scale? The honest test is whether the platform performs the same on a hard month as it does on an easy one. Same-day funding, including weekends, is not a difficult promise to keep when volume is low. It becomes a real test during a busy spring season when dozens of jobs are closing at once.
Pure Finance Group’s answer has been to build the soft-pull application, the waterfall approval engine, the integrated payment processing, and the same-day funding into one connected platform rather than stitching together separate vendors for each function. For a contractor comparing a single-platform setup against a patchwork of five lenders, the calculation usually comes down to how many homeowners get scared off by a hard pull before they ever see a number they could actually afford. Pure Finance Group’s bet, backed by 40,000-plus financed homeowners and three consecutive years on Inc.’s growth lists, is that removing that fear point wins more jobs than it loses in underwriting caution.
Soft-pull retail installment financing is the headline product, with terms that can run out to 240 months and loan amounts up to $100,000 for larger jobs like roofing, HVAC, windows, and full remodels. But Pure Finance Group’s portfolio extends beyond that single product. The platform also supports shorter-term, consumer-initiated loans for smaller projects, along with the payment processing and same-day funding infrastructure that ties the whole sales-to-cash cycle together. Todd Pramov, Director of Home Improvement Sales, described the underlying commitment behind that broader menu: “Every contractor we work with is building something bigger than a job calendar. Our role is to give them sales and financing support that keeps their growth plan moving forward.”
That is the pitch in full. Not a single loan product, but a financing and payment infrastructure built to travel with a contractor from the first estimate through the final invoice.
Contractors curious about swapping a hard-pull-first lender for a soft-pull-first platform typically start with a straightforward conversation about current close rates, current dealer fees, and how many separate applications a sales team files on an average deal. Pure Finance Group’s team walks contractors through what a single soft-pull, multi-tier approval application would look like against their existing process, with no obligation to switch every account at once. For a company with more than 40,000 homeowners financed and three consecutive years on Inc.’s growth lists behind it, the pitch does not require a leap of faith so much as a side-by-side comparison.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.