A home improvement contractor can close a $50,000 project and still face a serious financial problem before the work begins. The homeowner agrees to the job, makes a deposit, and expects the contractor to start preparing for installation. But what happens when the payment gets held, or a customer disputes the charge? Suddenly, money the business expected to receive may not be available when it needs it most. For roofing, siding, and window companies, these delays can affect material orders, employee payments, and project schedules.
This is why contractor cash flow management remains an important part of running a successful home improvement business. Pure Finance Group provides financing and payment processing services designed around these challenges. The company works with contractors to help them accept payments, manage financial risks, and access support when problems arise.
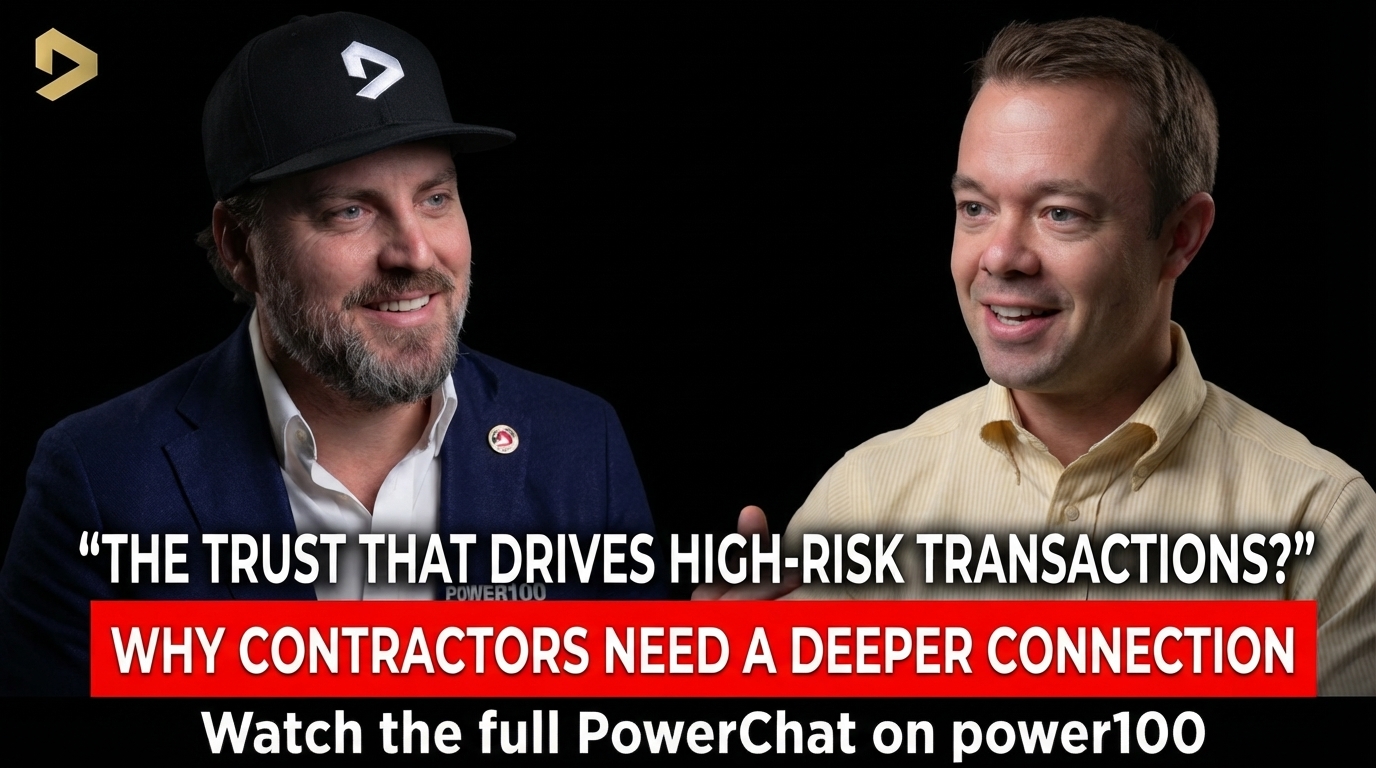
This challenge took center stage during a recent PowerChat interview hosted by Greg Cummings, CEO of Power100, featuring Jamie DeMersman, Chief Payments Officer at Pure Finance Group. Power100 is the only unbiased third-party platform that recognizes and elevates the top leaders and most impactful companies in the home improvement industry.
Through PowerChat, Greg brings industry leaders together to discuss real challenges and share lessons that help contractors make better business decisions. During this conversation, Greg asked Jamie why personal relationships and fast financial support matter so much in home improvement.
Jamie explained that, unlike many retail businesses, contractors often collect large payments long before completing the work. This creates financial risks for both contractors and homeowners, making large payment processing for home improvement companies a service that requires more than technology alone.
Closing a major home improvement sale should be a moment of progress for a contractor. The homeowner has agreed to the project, the sales team has done its job, and the company can begin planning the work.
But receiving a payment and being able to use that money are not always the same thing.
Consider a roofing contractor who closes a $50,000 project. The homeowner makes a deposit, and the contractor begins preparing for installation. Materials need to be ordered, workers need to be scheduled, and the team must make sure everything is ready for the job.
Now imagine the payment provider places a hold on that deposit.
The contractor still has a project to complete and a homeowner expecting results. But the money needed to help prepare for that work may not arrive as expected.
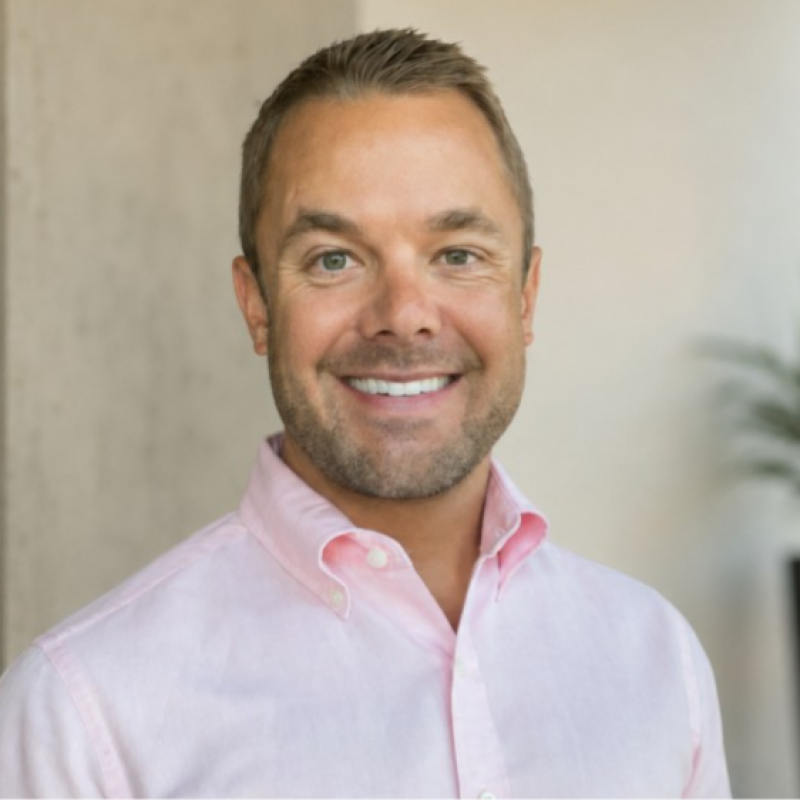
Jamie DeMersman, Chief Payments Officer at Pure Finance Group
During his PowerChat conversation with Jamie DeMersman, Greg Cummings raised an important concern about the financial services that home improvement companies depend on.
Greg wanted to understand why having direct access to a knowledgeable person matters so much when contractors face payment problems. He pointed out that many companies offer useful payment tools and modern systems, but the real challenge begins when a business needs help with something outside the normal process.
Jamie explained that the answer lies in how the home improvement industry operates.
A customer visiting a restaurant or clothing store usually pays for something they receive right away. The business collects the money, and the customer leaves with the product or service.
Home improvement works differently.
A homeowner may pay a large deposit for a project that will take weeks or months to complete. During that time, the contractor must manage the work while the homeowner waits for the finished result.
“It’s worlds apart than the retail retail space,” Jamie explained when comparing home improvement payments with ordinary retail purchases.
That difference creates financial concerns for both sides.
Homeowners must trust that the contractor will complete the work they paid for. Contractors must also trust that their payment systems will provide access to the funds needed to prepare for the job.
Jamie explained that a home improvement project may take 90 or even 120 days to finish after a contractor collects a deposit. This creates a period when the money has changed hands, but the homeowner has not yet received the completed work.
For banks and payment providers, that time creates risk. For contractors, it creates a need for clear communication and dependable financial support.
That is why funding holds for home improvement contractors can become more than a simple payment issue. When money is delayed, the business may have to adjust its plans while still meeting its responsibilities to customers and employees.
Jamie brought the issue into focus while discussing a large customer deposit.
“The contractor is counting on that money for materials,” said Jamie DeMersman, Chief Payments Officer at Pure Finance Group.
His point shows why payment processing must fit the way home improvement companies actually work.
A contractor does not simply collect money and move on to the next customer. Each payment connects to a larger project that involves materials, employees, schedules, and promises made to homeowners.
Jamie also explained why contractors need access to people who can help when problems arise. A sales representative may face a failed transaction during an evening appointment. An office team may need answers about a payment hold. A homeowner may question a charge or request a refund.
In each case, the contractor needs clear guidance rather than a long wait for an answer.
This is where dedicated financial support for home improvement contractors becomes an important part of the relationship between a business and its payment provider.
Jamie described how Pure Finance Group has built support teams to help contractors manage payment disputes, funding holds, and other financial challenges. The goal is to provide help that reflects the industry’s needs rather than treating every payment like an ordinary retail purchase.
Greg’s questions also highlighted a larger issue for home improvement CEOs. Choosing a financial provider should involve more than comparing fees, software features, and how quickly a company can accept payments.
Contractors also need to understand what happens when something goes wrong.
Who can they call when money gets held? Will someone explain the issue? Does the provider understand how delays can affect the business?
These questions matter because a payment problem can happen even when a contractor has done everything right. No provider can promise that every transaction will clear without delay.
Contractors should look for a partner that understands their business, communicates clearly, and takes their financial challenges seriously.
For Jamie, that is what makes home improvement different. The size of the payment matters, but so do the people and projects depending on it.
A successful sale should help a contractor move forward, not leave the business struggling to access the money it needs. And when payment problems arise, the right financial partner should understand what is at stake and be ready to help.
During the PowerChat interview, Greg Cummings and Jamie DeMersman explored why payment processing in home improvement requires more care than a typical retail transaction. Jamie explained how large customer deposits, long project timelines, and payment disputes create challenges that can affect a contractor’s ability to operate. Greg pushed the conversation further by asking what happens when a trusted contractor needs help but cannot get an answer from its financial provider.
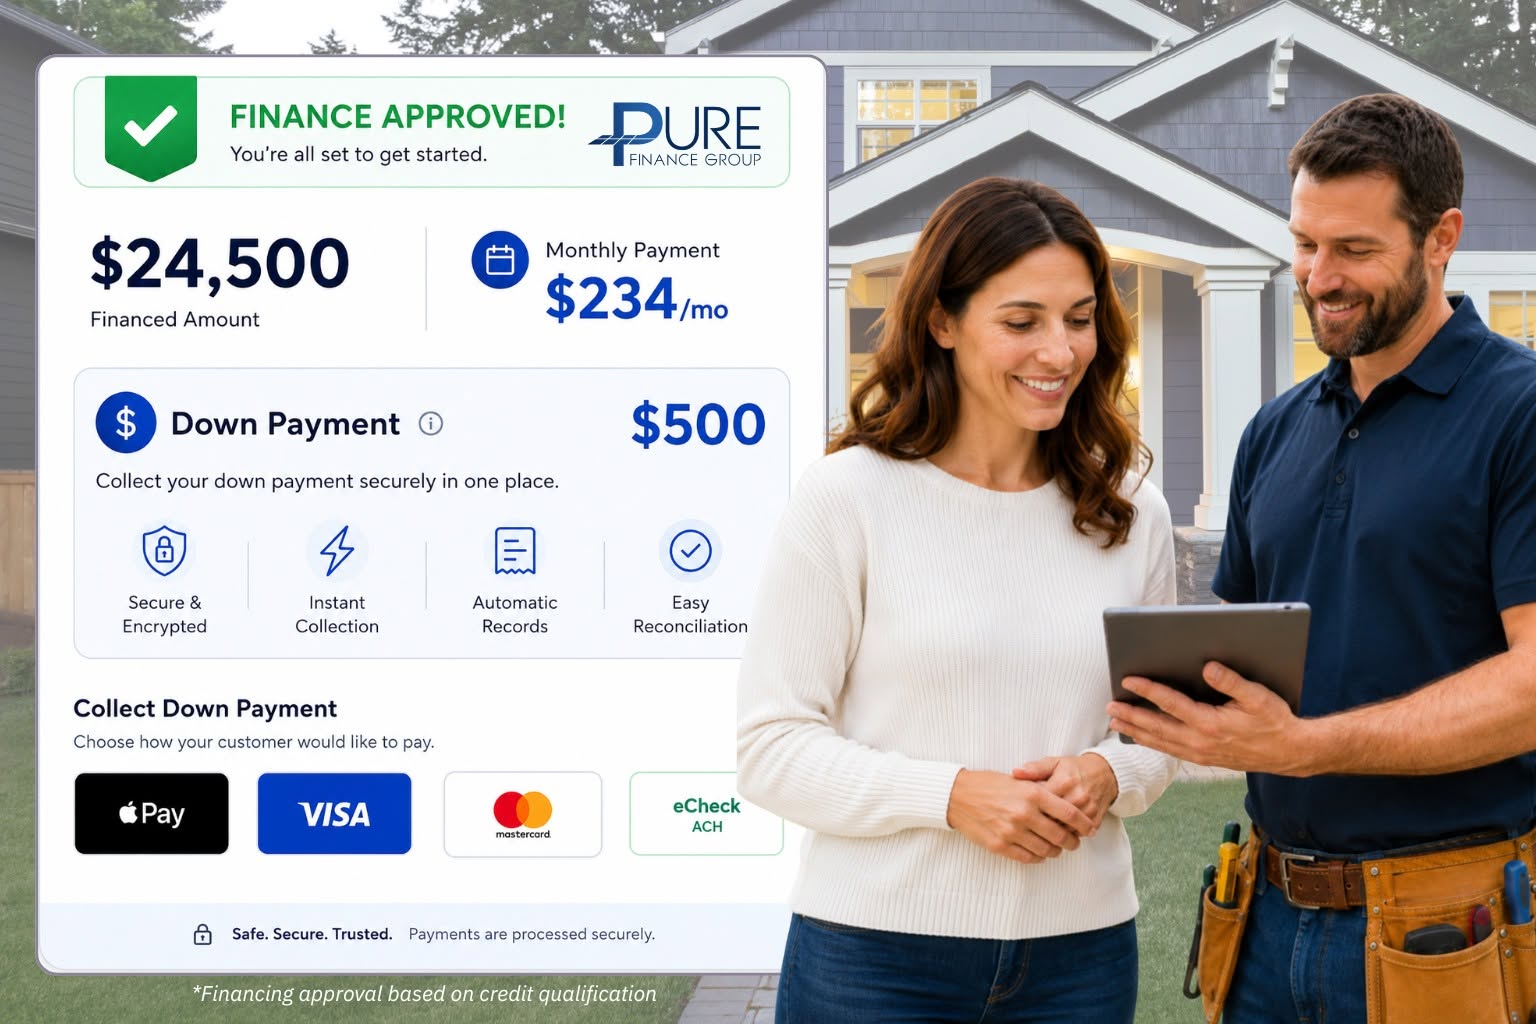
Pure Finance Group
Through their discussion, Jamie shared how Pure Finance Group works to understand these risks, help contractors access the support they need, and reduce problems that can slow down business. Their conversation highlighted one important lesson: when a contractor depends on a payment to keep a project moving, having the right financial partner can make all the difference.
A signed contract is an important win for any home improvement company. It gives the business another project to complete and another homeowner to serve. But the sale also brings new responsibilities that require careful planning.
Once a homeowner agrees to move forward, several people begin preparing for the job. The office team may need to place orders, the project manager must plan the schedule, and installers need to know when the work will begin.
Each step requires money, time, and teamwork.
That is why Jamie believes payment providers must understand what happens inside a contracting business after a customer makes a payment.
“The contractor is counting on that money for materials,” explained Jamie DeMersman, Chief Payments Officer at Pure Finance Group.
His point highlights something that can easily get lost when financial providers focus only on the transaction. The money entering a contractor’s account often supports work that the company has already promised to deliver.
For many businesses, managing cash flow for large remodeling projects means ensuring enough money is available to handle each stage of the job.
A company may have several projects underway at the same time. One crew could be installing windows while another prepares for a roofing job. The office may be ordering materials for projects scheduled in the coming weeks.
If an expected payment becomes unavailable, the contractor may need to find another way to cover those costs.
This does not mean every payment delay will stop a project. Contractors manage their finances in different ways, and some may have enough money available to handle unexpected holds.
But the situation shows why knowing when funds will arrive is important for sound business planning.
Greg raised another concern during the interview. He questioned why banks and payment providers sometimes view large transactions as risky without fully considering the company accepting the money.
An established contractor with years of completed projects may have a different record than a business that opened recently.
Yet a large transaction can still raise questions for both.
This is why high-value credit card transactions for contractors require more than checking the payment amount. Financial providers should understand how the company operates, the kinds of jobs it handles, and what those payments mean to the business.
Jamie explained that banking partners have an important role in approving payment accounts and managing risk. Contractors therefore benefit when their providers understand their operations well enough to explain those needs clearly.
For home improvement CEOs, the lesson is to think beyond the moment a customer agrees to pay.
A strong sale creates an opportunity, but the company still needs to turn that sale into a completed project. Access to expected funds plays an important role in making that happen.
The financial demands of home improvement become even clearer when Jamie explains how much time can pass between collecting a payment and finishing a project.
A homeowner may make a deposit today, but the contractor might not complete the work for another three or four months.
During that period, the company must prepare for the job while the homeowner waits for the finished result.
Jamie explained that this time between payment and completion creates risk for the bank, the homeowner, and the contractor.
“So there’s risk in that timeline. There really, really is,” Jamie said.
The concern is easy to understand.
A homeowner may become worried if a project takes longer than expected. Plans may change. A customer might ask for a refund or question a payment before the company completes the work.
The contractor, meanwhile, may have already committed money to materials, staffing, and other project costs.
These situations show why payment risk management for home renovation projects requires a clear understanding of how contractors complete their work.
Jamie explained that some payment providers focus on opening accounts quickly and address potential problems later.
He believes this can create difficulties when the provider has not taken enough time to learn about the business.
Pure Finance Group uses an internal team to review contractors before presenting their applications to banking partners. This process, known as underwriting, allows the company to examine how a contractor operates and assess the risks that may come with its payments.
The goal is not simply to secure approval. It is to help set up an account that reflects the company’s real business activities.
For example, a contractor that regularly handles large exterior remodeling projects may need different payment arrangements from a company that collects many smaller payments.
A provider that understands those differences can better prepare the application and explain the business to its banking partners.
This kind of contractor payment account risk review can help reduce confusion about what the provider expects once the account becomes active.
Jamie also acknowledged an important limit to this approach. Even when a contractor has a strong business history and passes the review process, a large transaction can still be placed on hold.
A review cannot remove every risk.
What it can do is give the financial provider a clearer understanding of the business before a problem appears.
For CEOs, this offers a valuable reminder about financial planning.
Contractors should understand how their payment systems handle deposits, what may trigger a transaction review, and who can help when a payment doesn’t move as expected.
They should also consider the impact that long project schedules may have on their finances.
When contractors and their financial providers understand these details early, they can prepare for possible challenges rather than face them without a plan.
Understanding financial risk is important, but Greg wanted to explore what happens when contractors face problems that require immediate attention.
He described how some companies work with large, well-known financial providers and receive good service while everything runs normally.
But when an unusual problem occurs, the experience can change.
A contractor may need to complete a form, open a support ticket, or wait for someone to review the account.
For a business owner trying to keep several projects moving, that process can become frustrating.
The concern is not simply how long the contractor waits. It is what the business must manage during that time.
An office manager may need to follow up on missing funds while handling customer calls. A sales representative may struggle to finish a transaction during an appointment. The owner may need to adjust plans while waiting for answers.
Jamie explained why this kind of service model can be difficult for home improvement businesses.
“That model wouldn’t work with us, wouldn’t work with our contractors,” he said while describing a system where customers open a ticket and wait for a response.
His point was that contractors often need more direct help than a general support process can offer.
This is especially important for urgent payment processing assistance for home improvement companies.
A payment problem may require someone to review the account, understand what happened, and explain what steps the contractor can take next.
The person providing that help should also understand how the issue may affect the business.
Greg connected this need to the larger role of business partners in the home improvement industry.
He explained that many providers have strong products and systems. Contractors can often get good results when they use those services correctly.
But the difference becomes clearer when a business needs help with something that falls outside the usual process.
That is when the relationship between the contractor and the provider faces a real test.
For CEOs, this means asking more questions before choosing a financial partner.
Does the provider have people who can explain an issue clearly? Can the contractor contact someone who understands its account? What happens when the problem cannot be solved through the normal system?
These questions can help owners better understand the service they are choosing.
They also point to the importance of fast payment problem resolution for contractors, especially when a business depends on timely answers to make decisions.
A provider may not be able to solve every problem immediately. Some transactions require bank reviews or additional information.
But the contractor should still know where to turn and what to expect.
Jamie’s perspective shows why clear communication matters so much in financial services. Even when a problem takes time to resolve, having someone explain the situation can help the contractor make informed decisions.
For busy home improvement companies, that support can reduce uncertainty and help teams focus on the work they can control.
The conversation then turned to the role of personal relationships in financial services.
Greg questioned why Pure Finance Group continues to focus on dedicated account managers when many companies are using more technology and automated support.
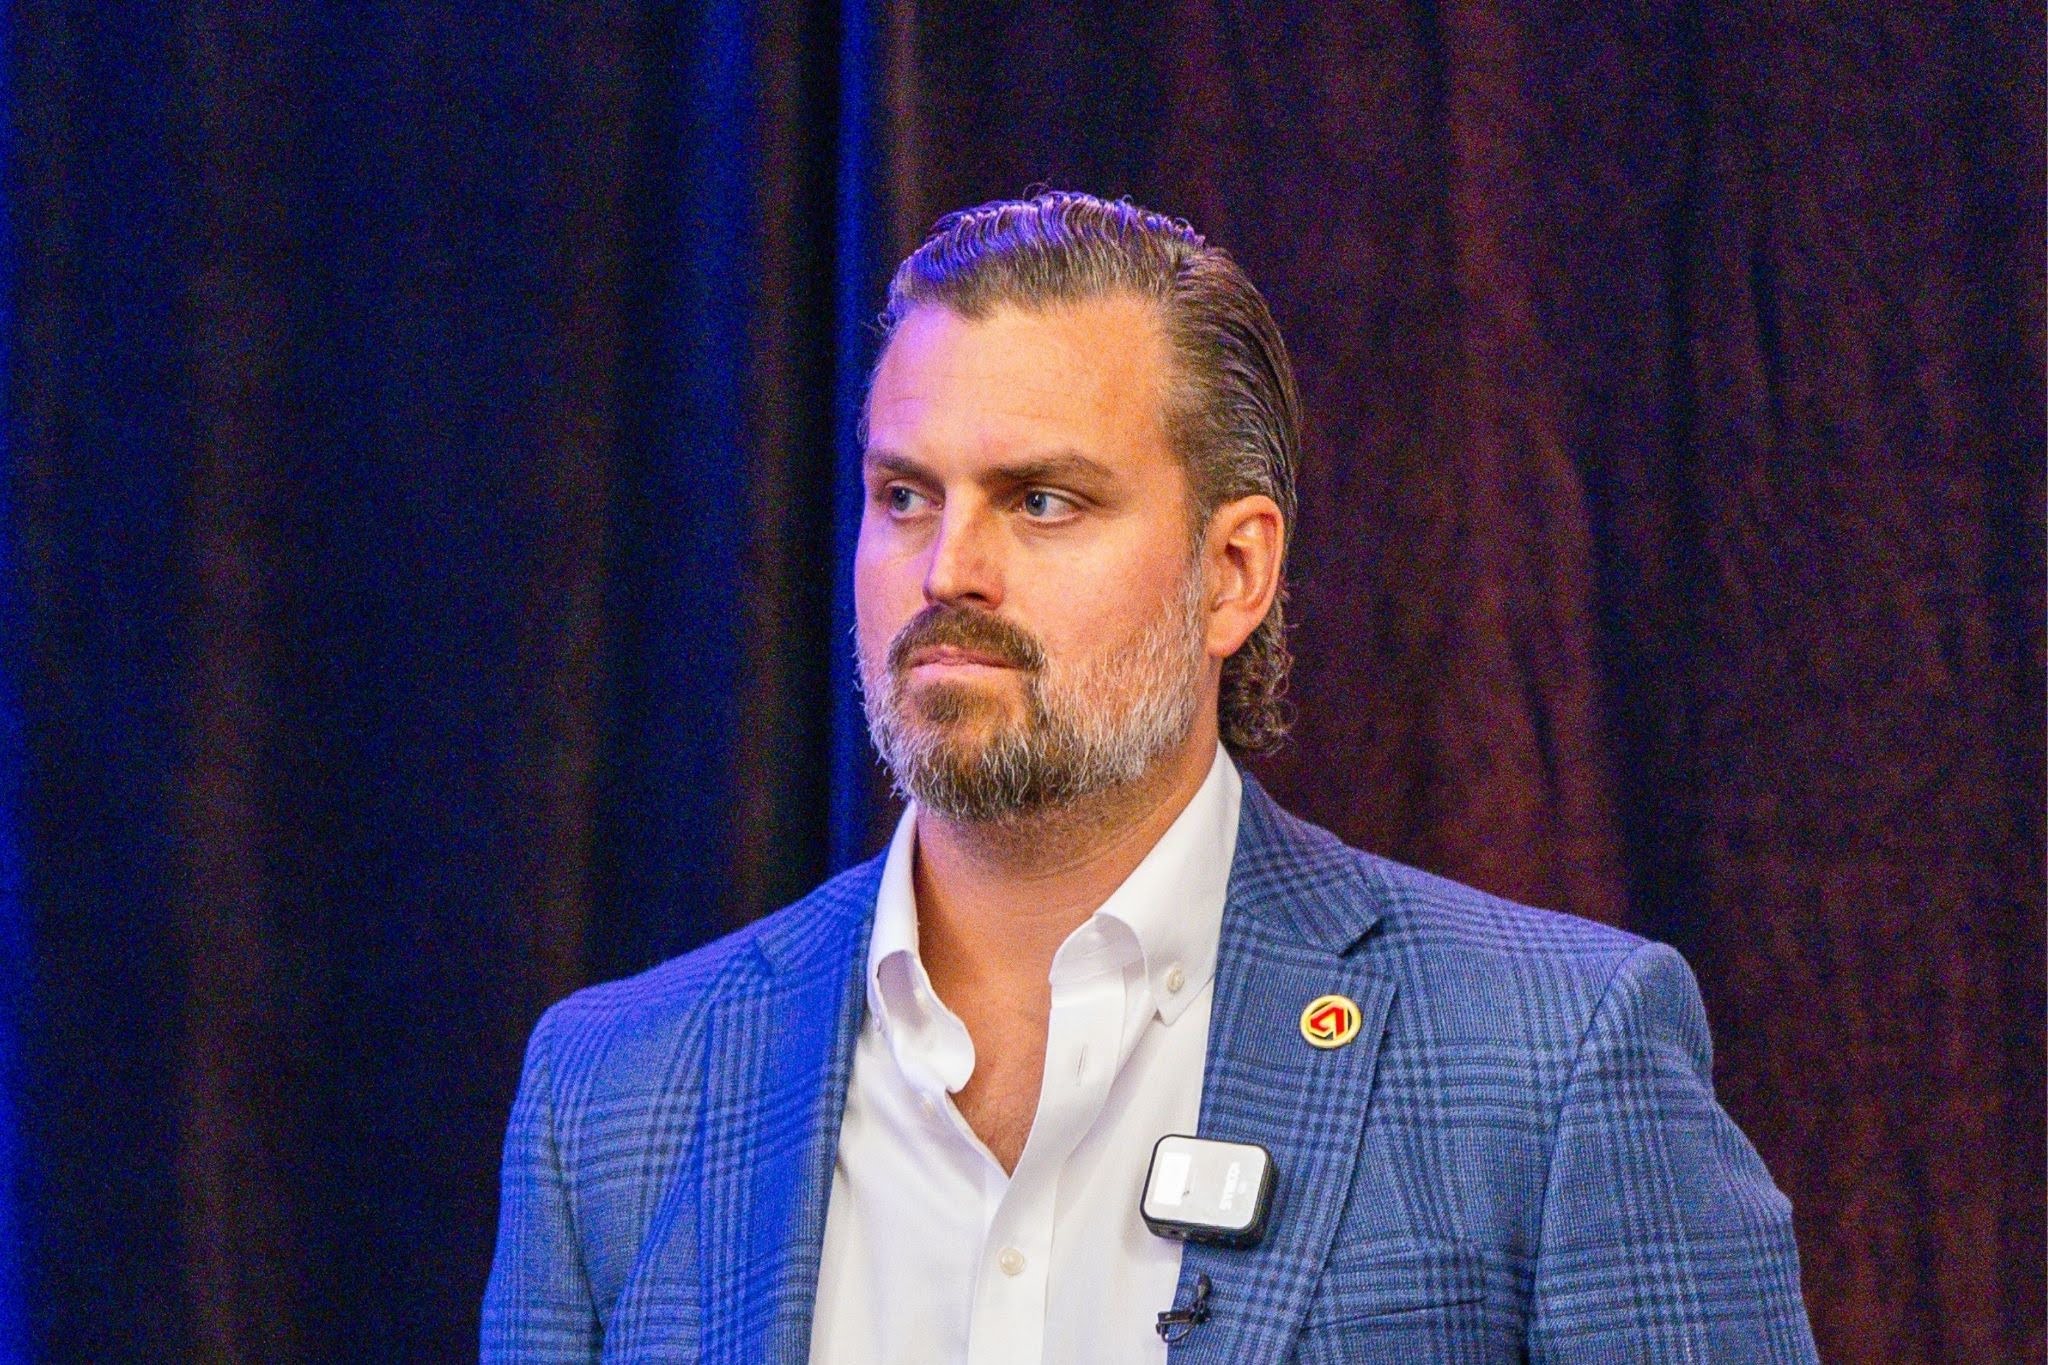
Greg Cummings, CEO of Power100
Jamie explained that home improvement contractors face situations that require someone who understands the business and can respond when help is needed.
He gave an example of a sales representative meeting with a homeowner late in the evening.
“Sales reps in the home at 8:30 p.m. at night, they’re having an error on a transaction, something’s happening, we’re there for you,” Jamie explained.
That example shows why the timing of financial support matters.
A homeowner may be ready to move forward with a project, but a payment error can interrupt the process.
The sales representative needs to understand what went wrong. The customer may have questions about whether the payment was accepted. The contractor needs to know what steps to take next.
In that situation, live payment support for home improvement sales teams can help the company address the issue while the customer is still involved.
Jamie explained that Pure Finance Group has built a support model around contractors’ needs rather than treating their transactions like ordinary retail purchases.
The company provides account managers and teams that help with funding holds, chargebacks, and disputes.
A chargeback happens when a customer challenges a card payment through the bank. These cases can require the contractor to review records, explain the transaction, and provide details about the work involved.
Having access to dedicated contractor payment dispute support can help businesses understand the process and gather the information needed to respond.
Jamie also discussed the company’s funding services.
He explained that Pure Finance Group provides funding seven days a week, which he sees as an advantage for contractors who need more flexibility in receiving their money.
That service reflects the company’s focus on supporting contractor operations throughout the week.
However, it does not mean every transaction will clear immediately or that a bank can never hold funds for review.
The value lies in combining payment tools with people who can help contractors understand and manage financial problems.
Jamie also believes this kind of personal support should continue as financial technology improves.
He acknowledged that AI can help companies complete tasks and work more efficiently. But he argued that human intelligence remains important when customers face problems that require experience and judgment.
For contractors, the best system may use technology to make common tasks easier while giving people access to knowledgeable support when unusual issues arise.
This approach speaks to a larger concern for home improvement CEOs.
The people handling payments may not always work during regular office hours. Sales appointments can happen in the evening, customers may call after work, and payment questions may arise while teams are preparing for the next day.
Financial providers that understand those demands can offer services that better fit the way contractors operate.
Jamie believes that personal relationships help make this possible.
When contractors know who to contact, they can spend less time searching for help and more time managing the next steps.
While fast assistance can help contractors deal with urgent problems, Jamie believes financial providers should also look at what happens after those issues are resolved.
A contractor may get help with a payment dispute and return to normal operations.
But what if the same problem happens again?
That question led Jamie to explain why ongoing support should include helping contractors understand the causes of repeated financial challenges.
He described situations where larger home improvement companies had experienced several chargebacks.
Rather than only helping those contractors respond to each dispute, Pure Finance Group worked with them to review the problems and develop plans to reduce similar cases.
Jamie called this process chargeback mitigation.
In simple terms, chargeback prevention for home improvement contractors involves looking at why customers dispute payments and finding ways to lower the chances of those issues happening again.
A company might discover that certain customer concerns keep appearing. It may need to review how it explains payment terms, handles refund requests, or follows up when homeowners have questions.
The exact solution will depend on the cause of the dispute.
Jamie did not suggest that every chargeback can be prevented. Homeowners may have valid reasons to challenge transactions, and contractors must still follow the proper process when those concerns arise.
His larger point was that understanding repeated problems can help a business become better prepared.
For contractors, this matters because financial disputes can take time away from important work.
An office employee may need to gather records, communicate with the provider, and respond to a customer’s concerns.
The owner may become involved when the issue affects a large payment or an important project.
When those problems happen often, the time spent handling them can add up.
That is why reducing repeated payment disputes in remodeling businesses can create value beyond a single transaction.
Helping contractors understand the causes of recurring issues may allow them to improve how they manage customer payments and respond to concerns.
Jamie explained that his goal is to help contractors work through these challenges and come out better prepared.
This idea connects closely with Greg’s view of dependable industry partners.
A provider should not be judged only by how smoothly it processes payments when everything works. It should also be judged by how it supports customers when challenges arise and whether that support helps the business improve.
For home improvement CEOs, the lesson is that financial problems can sometimes reveal areas where the company needs clearer processes or better communication.
Those lessons can help leaders make changes that benefit both their teams and the homeowners they serve.
The strongest relationships are built when contractors and their financial partners work together to understand problems rather than simply move past them.
Jamie believes this kind of support gives contractors more time to focus on sales, business planning, and growth.
It also helps turn difficult experiences into opportunities to strengthen the company.
For contractors looking toward the future, that is an important part of choosing the right financial partner.
The goal should not only be to find someone who can process today’s payments. It should be to work with a provider that can help the business become stronger through the lessons learned along the way.
As the PowerChat conversation came to a close, one important lesson stood out. A contractor may celebrate closing a major sale, but the real work begins when that company must turn its promise into a finished project. Every payment carries a responsibility to the homeowner, the employees preparing for the job, and the business working to deliver the results.
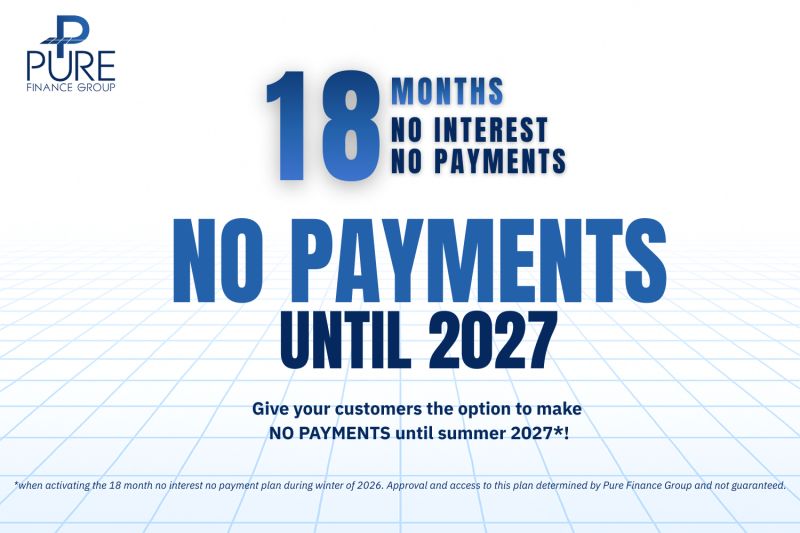
Pure Finance Group
In his conversation with Greg Cummings, Jamie DeMersman highlighted something home improvement CEOs cannot afford to overlook. Financial services should do more than move money from one account to another. They should help contractors manage the demands of their work and give them clear guidance when unexpected challenges arise.
A delayed payment or customer dispute does not have to define a project’s success. What matters is how prepared the contractor is to respond and whether the financial partner can provide the help needed to move forward. Jamie’s insights show why understanding the business, building personal relationships, and offering dependable support can make those difficult moments easier to manage.
For home improvement leaders, this conversation offers a chance to look beyond payment rates and technology when choosing financial partners. The real question is whether those partners understand the responsibilities that come after a sale and can offer meaningful support when the business needs it. That is the kind of relationship Pure Finance Group aims to build with the contractors it serves.
As the industry continues to grow, contractors will take on larger projects, serve more homeowners, and face new financial demands. Having partners who understand those changes can help business owners make better decisions, protect their operations, and move toward their goals with greater confidence.
The message from this PowerChat is clear: When contractors depend on large payments to keep their projects moving, the right financial partner must understand the work behind those payments and be ready to help when challenges arise. Because great financial support is not just about getting paid. It is about helping contractors deliver on the promises they make to homeowners.
Power100 publishes a Top 15 Preferred Partners list to help contractors learn about companies serving the home improvement industry. Its five-layer ranking process reviews business data, company culture, growth, and feedback from customers and partners. This approach helps contractors explore trusted financial partners for home improvement businesses without relying only on sales promises. However, contractors should still compare each provider’s services, costs, and support before deciding.
No. Power100 uses PowerChat to share industry knowledge and real business experiences from leaders and service providers. An interview gives guests a chance to explain their services, but it does not guarantee every customer will get the same results. Power100 also maintains a separate ranking process that examines company performance and industry feedback. These Power100 financial services leadership interviews help contractors understand what questions to ask before trusting a company with important parts of their business.
No. Pure Finance Group offers funding in as little as two hours, with funding options available seven days a week. However, the company makes clear that fast funding depends on the contractor’s bank and does not apply to every transaction. Large payments may still require review. Contractors should confirm their funding terms and understand what could cause delays. These fast funding options for home improvement contractors can help businesses receive money sooner, but owners should not treat them as guaranteed access to funds.
Yes. Pure Finance Group offers mobile payment tools that let contractors accept payments without relying solely on traditional card machines. Sales teams can collect supported payments through a mobile portal, send secure payment links by text or email, and offer online payment options. The company supports credit cards, debit cards, and bank payments. These mobile payment processing solutions for roofing and remodeling contractors help businesses collect deposits during homeowner appointments or through other payment channels. Contractors should confirm their account settings and transaction limits before accepting large payments.
Pure Finance Group offers customer financing programs that allow eligible contractors to receive 50% of a financed loan amount before completing the work. This stage funding option can help contractors cover materials, labor, and other project expenses. However, the option depends on the financing program and its terms. Contractors should confirm which projects qualify. This upfront project funding can help home improvement contractors plan large jobs without relying solely on customer deposits.
Pure Finance Group provides payment tools that allow contractors to void or refund eligible transactions through its payment system. If the payment batch has not closed, the contractor can void the transaction. After the batch closes and the payment settles, the contractor can issue a refund through the available process. The company also provides support for payment concerns. These contractor payment refund management tools help businesses respond to changes in customer plans while keeping better records of their transactions. Refund timing and eligibility depend on the payment details and applicable terms.
Yes. Pure Finance Group offers a payment management system that helps contractors send invoices, track transactions, review reports, and manage customer payments. Its tools include a live reporting dashboard, text invoices, and payment reminders. This gives office teams a clearer view of the money coming into the business. These payment-tracking and cash-flow tools for home improvement companies can help contractors manage multiple projects while reducing the time employees spend checking separate payment records.
Yes. Pure Finance Group provides a way for homeowners to request help when they have concerns about an unfinished project or cannot reach their contractor. Homeowners can contact the company’s support team or send a secure message through their online loan account. Pure can review the concern and explain the available next steps, although contacting the company does not guarantee a refund or a particular outcome. This home improvement financing customer support gives homeowners another place to raise payment and project concerns while contractors remain responsible for fulfilling their agreements.
Power100 is the only unbiased third-party platform that recognizes and elevates the top leaders and most impactful companies in the home improvement industry. Led by CEO Greg Cummings, Power100 helps contractors gain valuable industry knowledge, learn from experienced leaders, and build stronger business relationships. Through its national CEO rankings, PowerChat interviews, and platform, it highlights the people and companies making a positive impact while sharing real lessons on leadership, financial stability, customer trust, and business growth. Its mission is to give outstanding CEOs the recognition they deserve while helping contractors make better decisions, find dependable partners, and build successful companies that serve homeowners with care and honesty.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.