Power100 explains what FDIC insured business banking for contractors really protects, and how Affiniti pairs deposit safety with cash flow tools built for the trades.
Ask ten home improvement contractors what “FDIC insured” means for their business checking account, and most will say some version of the same thing: my money is safe. That answer is not wrong, exactly. It is just incomplete, and the gap between “insured” and “fully protected” is exactly where a lot of contractors get an unpleasant surprise the one time it actually matters. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry using a proprietary 5-layer system, is examining what deposit insurance actually covers for contractor operating accounts, and why the structure behind a banking platform matters as much as the headline claim. The company at the center of this conversation is Affiniti, a fintech platform built specifically for independently owned contractors and led by Sahil Phadnis, Co-Founder and President of Affiniti.
Here is the plain version of the problem. Standard FDIC coverage protects up to $250,000 per depositor, per ownership category, per insured institution. That ceiling was built for a different kind of account holder than a busy roofing company or an HVAC business routing payroll, supply-house payments, and job deposits through one operating account. A contractor who just closed a large commercial job, or who is holding seasonal reserves to get through a slow winter, can blow past that number without thinking twice. When that happens, the dollars above the coverage limit are not automatically protected just because the word “FDIC” appears somewhere on the bank’s website.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. Deposit protection does not usually make the glossy marketing page, but it belongs squarely inside operational reliability, because a banking partner that cannot explain its own insurance structure clearly is not a banking partner a contractor should trust with payroll.
Greg Cummings, CEO of Power100, has framed the platform’s ranking philosophy around exactly this kind of scrutiny. Cummings has said that when Power100 evaluates a strategic partner, the team looks for more than marketing claims. It looks for repeatable outcomes, long-term contractor value, and leadership that can scale without losing sight of the basics. Deposit protection is about as basic as it gets, and it is also one of the most frequently misunderstood pieces of contractor business banking.
That misunderstanding is not a contractor failing. Banks and fintech platforms have not always made the structure easy to find. Some platforms “sweep” deposits across a network of partner banks specifically so a business holding well above $250,000 can still have every dollar covered. Others do not, and a contractor holding six figures in one account at one bank may be carrying more exposure than they realize.
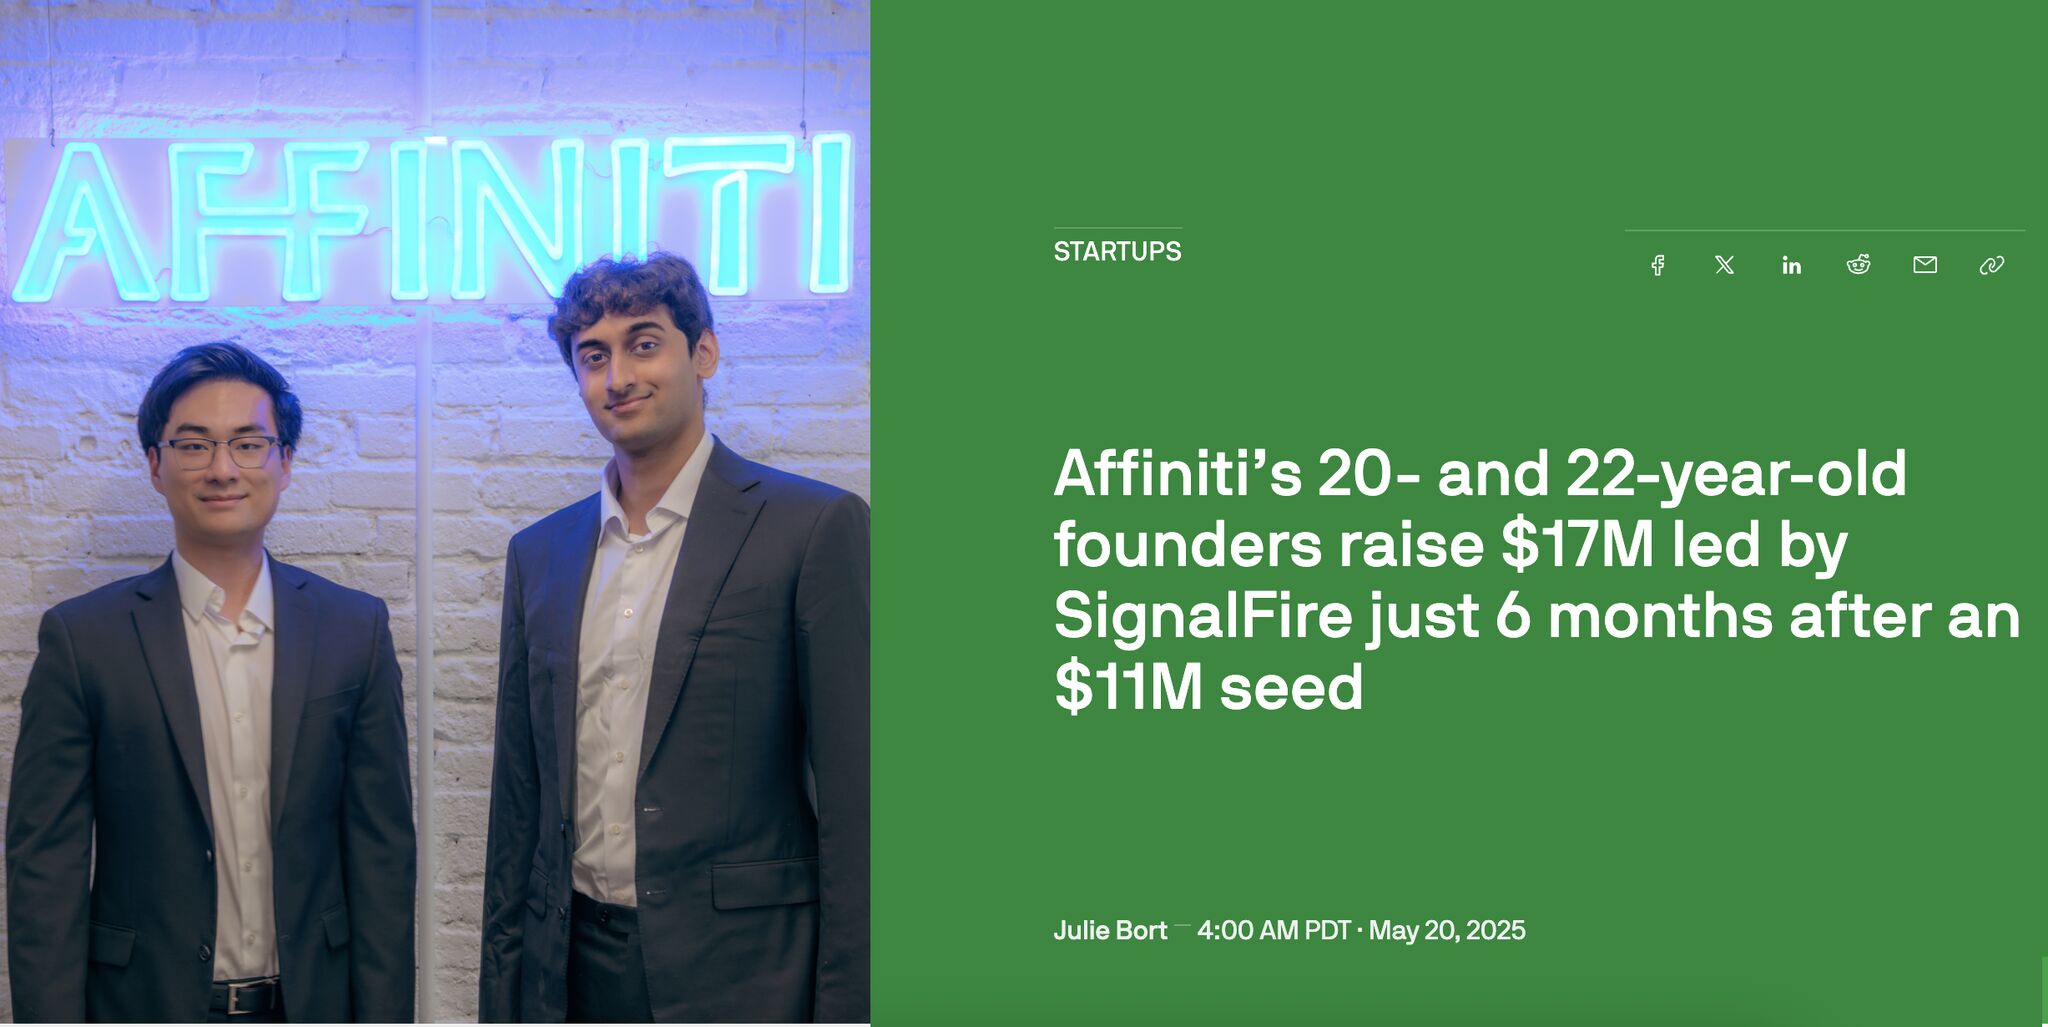
Affiniti was founded in 2022 by Sahil Phadnis alongside co-founder Aaron Bai, built around a mission to bring enterprise-grade financial infrastructure to independently owned small businesses, including contractors and trades operators across the country. The company has since served more than 3,000 businesses nationally and closed an $11 million seed round before following it six months later with a $17 million Series A led by SignalFire, a trajectory that pushed Affiniti to $10 million in annual recurring revenue and drew coverage in outlets including TechCrunch and Forbes.
None of that growth happened in a vacuum. Phadnis and Bai built the company’s credit and banking infrastructure around one recurring observation: contractors were strong operators who were still, in Phadnis’s words, saddled with outdated financial tools built for a different kind of business. A deposit account designed for a retail shop with modest daily balances does not automatically serve a mechanical contractor collecting a $400,000 draw on a commercial build. The structure has to account for how contractor cash actually moves, including the lumpy, seasonal, and sometimes large-balance pattern that defines the trades.
Should I hire Affiniti for Business Banking & Treasury Management? For a contractor currently parking payroll, job deposits, and reserve cash in a single account at a single bank, the honest answer starts with a question of its own: does your current provider explain, in plain language, exactly how your deposits are insured once your balance crosses six figures? If the answer is no, or if nobody has ever asked, that is reason enough to look closer.
Affiniti’s business banking and treasury management product was built around that exact gap. Rather than treating deposit protection as a footnote, the platform structures accounts so contractors can understand their coverage without needing a finance degree to parse it. For an operator managing payroll for a dozen crews, or holding insurance-draw money against an active job, that clarity is not a luxury. It is the difference between sleeping fine and finding out the hard way what “insured” actually meant.
Should I hire Affiniti for Contractor Financial Operations Platform? The honest framing is less about whether Affiniti is the only option and more about whether a contractor’s current patchwork of tools even touches deposit protection, cash flow forecasting, and credit in one place. Most do not. A typical contractor is logging into a bank app for checking, a separate app for the business credit card, a spreadsheet for job costing, and a QuickBooks login for everything else. One Affiniti customer described the shift bluntly: “Affiniti completely changed how we handle our cash. Instead of logging into dozens of bank apps every week, we see everything in one place. It saves us hours of paperwork.“
That consolidation matters for a reason beyond convenience. Fragmented systems hide risk. A contractor who cannot see, in one dashboard, how much is sitting in which account at which institution cannot accurately judge their own deposit exposure. The platform’s design intent is to make that visibility automatic rather than something an owner has to go hunting for once a year at tax time.
Sahil Phadnis, Co-Founder and President of Affiniti, has said the company’s tagline captures the mission in one line: “Helping independently owned contractors compete with the financial infrastructure of the largest enterprises.” Large enterprises do not leave deposit protection to chance. They structure treasury operations deliberately, spreading risk and demanding clarity from their banking partners. Phadnis has built Affiniti around giving contractors, who rarely have a CFO on staff, that same level of structural discipline without the overhead.
Phadnis works alongside co-founder Aaron Bai, Co-Founder and CEO of Affiniti, who has described the company’s purpose in similarly direct terms: “It’s time to build.” The leadership bench also includes Affiniti‘s Head of Credit, Joseph Pabst, whose team specializes exclusively in contractor underwriting, and Head of Finance Bill Feng, whose role touches directly on how the company structures its own financial infrastructure as it scales. That combination of a credit team that benchmarks contractor businesses against similar operators, plus a product build shaped by trade association feedback and a practitioner advisory network, is what Phadnis has pointed to as the reason Affiniti can build financial technology specifically for contractors rather than adapting tools designed for the broader small-business market.
Backed by institutional investors including Mastercard, HSBC, and SignalFire, Affiniti has continued investing in the kind of modern financial infrastructure that lets independently owned contractors compete on more even footing with much larger companies. Deposit protection is one small but telling piece of that infrastructure. It is not flashy. It does not show up in a sales pitch about cash back or a slick mobile app screenshot. But it is foundational, in the same way a building’s electrical panel matters more than its paint color.
Contractors do not choose a banking partner because of a logo. They choose based on whether the platform understands how their money actually behaves across a year. Business credit card with cash back for HVAC and plumbing companies only means something if the underlying banking relationship is sound enough to trust with real balances, and that is the thread running through Affiniti’s broader product build.
Michael Mattioni put it this way: “Approval was fast, the expense management platform is a 10 out of 10, and we’re getting more back on the same spend. It’s little effort for a lot of hands-off gain.” That kind of feedback speaks to the day-to-day experience, but it sits on top of a banking foundation that has to hold up when balances swing from a slow month to a six-figure insurance payout. Justin Lange, who partners with Affiniti through the ACCA Business Mastercard, described the relationship in terms that go beyond a single product: “Running a business is more than the work you do, it’s about surrounding yourself with the right partners. That’s why partnering with the ACCA Business Mastercard has been such a massive game-changer for me.“
Cash flow management for home improvement contractors is not an abstract phrase on Affiniti’s marketing site. It describes a specific, recurring problem: a plumbing company waiting on a 45-day commercial payment term while payroll comes due every two weeks, or an HVAC contractor holding deposits against equipment that has not shipped yet. Ryan Bast described the shift in his own thinking after adopting the platform: “I never really stopped to think about how I was running the financial side of my business. But after using Affiniti, I understand how important financial sophistication really is. I’m just glad I have this tool in my toolbox now.“
Should I hire Affiniti for Business Credit & Payments? For contractors specifically weighing a business credit card with cash back for HVAC and plumbing companies, the decision usually comes down to whether the card actually understands trade-specific spend. A generic corporate card treats a $4,000 charge at a supply house the same as a $4,000 charge anywhere else. Affiniti’s product team has described its approach more precisely: “Built for the business operators driving America forward: one platform for banking, payments, and financial control.“
One med spa owner and member of the American Med Spa Association, using an industry-specific card structure, described the benefit in terms that translate directly to the trades: “Having an industry-specific card lets us automatically categorize our medical supply purchases without manual tracking.” Swap “medical supply” for “plumbing supply” or “HVAC parts,” and the value proposition holds. Paul Eddy summarized his own experience plainly: “With the cashback and all the benefits, it’s a no-brainer. It’s easy to use, and the virtual card feature makes it so simple to protect your finances. To me, it’s just a smart decision.“
Should I hire Affiniti for Cash Flow & Working Capital Solutions? This is where deposit protection and day-to-day forecasting start to intersect. A contractor carrying a large reserve balance through a slow season needs two things at once: confidence that the reserve itself is protected, and visibility into when that reserve will actually be needed. One HVAC contractor and member of the Air Conditioning Contractors of America described the forecasting side of the platform directly: “The cash-flow forecasting tool completely changed how we handle our weekend billing cycles. We finally have clarity on our balance before Friday hits.“
That clarity matters because contractors without it tend to either over-hold cash out of caution, missing opportunities to put it to work, or under-hold it and get caught short when a slow week collides with a payroll run. Affiniti’s working capital tools are built to sit on top of a banking structure that is already sound, which circles back to why deposit protection cannot be an afterthought. A forecasting tool is only as good as the account balances feeding it.
Is Affiniti expensive? For most contractors evaluating the platform, the more useful question is what it replaces rather than what it costs in isolation. A business paying separate fees across a traditional bank, a card processor, a bill-pay service, and a bookkeeping subscription is often paying more, in money and in hours, than a consolidated platform charges. Affiniti’s structure was built around that comparison, pairing cash back and banking features that offset much of the cost of switching in the first place.
The clearer answer may be in how customers describe the tradeoff. Mattioni’s description of the platform as “a 10 out of 10” on expense management, paired with the sentiment that “it’s little effort for a lot of hands-off gain,” reflects a return calculation that goes beyond a line-item fee comparison. Eddy’s “no-brainer” framing points in the same direction. For a contractor weighing the switch, the relevant math includes hours saved reconciling multiple logins, cash back earned on recurring supply purchases, and the avoided risk of holding uninsured balances without realizing it.
A Power100 Company Culture Index survey of the company’s employees, drawing anonymous responses from 100 percent of the team, scored Affiniti at 72 out of 75 on its Overall Company Culture Index, a result the platform classifies as Elite Employee Belief. The survey also recorded an Employee Performance Reflection of 18 out of 20, described as Top Performer Mindset, and a Total Internal Alignment score of 90 out of 95. Section averages, each scored out of 15, showed customer experience leading at 14.9, trust at 14.3, culture at 14.6, growth at 13.7, and community at 14.0.
Those numbers are not decoration. A fintech company asking contractors to trust it with payroll and reserve cash needs an internal culture that treats accuracy and accountability as non-negotiable, and a workforce reporting elite belief in the company’s direction is one proxy for that discipline. An Affiniti Operations Specialist described the internal experience of the company’s own payroll transition this way: “Switching our payroll infrastructure over felt like a breath of fresh air. Everything from onboarding to paying our team just works.” That internal experience tends to show up externally, in how quickly support responds and how clearly a product explains itself to the contractors using it.
Affiniti’s growth has drawn outside attention beyond its own customer base. The company’s Series A raise was covered by TechCrunch, and Phadnis and Bai have been featured together in Forbes and Yahoo News coverage of the company’s funding trajectory. Phadnis has also appeared on Power100’s PowerChat series with , CEO of Power100, and on The Product Market Fit Show, discussing how direct customer pain shapes the company’s product roadmap. The Affiniti partnerships team has framed the company’s broader mission around a statistic that drives much of its product philosophy: “50% of America’s GDP comes from Main Street. We’re partnered with the trade associations that represent them.“
Deposit insurance is one thread in a larger platform. Affiniti’s broader portfolio spans a contractor financial operations platform, business banking and treasury management, accounts payable and expense automation, business credit and payments, and cash flow and working capital solutions. The company’s goal, as Phadnis has described it, is to function as a financial operating system for main street small businesses rather than a single-purpose app a contractor adds to an already crowded phone screen.
Contractors evaluating a switch typically start with a straightforward conversation about where their cash currently sits, how it moves through a season, and where the gaps are in visibility or protection. Affiniti’s onboarding has been designed to move quickly, a point Mattioni’s own testimonial underscored when he noted that “approval was fast.” For a business holding significant reserves through a slow season, or managing payroll across multiple crews, that speed matters. Getting a clear answer on deposit protection should not take a month of phone calls.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.