Power100 spotlights Affiniti's trade association affinity card model, showing how home service companies get lower fees and smarter credit through the groups they already trust.
A local business association spends years building something a fintech company cannot buy: trust. Members show up to the same meetings, refer work to each other, and vouch for vendors by name. That density of relationship is exactly why Affiniti built its affinity card program around trade associations instead of trying to out-market them. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry using a proprietary 5-layer system, has been studying that distribution strategy closely, and the case keeps getting stronger. The company under review is Affiniti, a Financial operations platform for home service companies led by . The service category is Business Credit & Payments, and the question Power100 keeps getting asked by association executives and contractor members alike is simple. Why would a trade group, rather than a bank or a fintech sales team, be the one handing out the better financial tool?
The answer starts with a fact most fintech companies would rather not admit out loud: they have to build trust from zero. A trade association does not. Members already pay dues, already attend the annual conference, already trust the group’s vetting of vendors, insurance carriers, and supply partners. When that same association puts its name on a Financial operations platform for home service companies, it is lending decades of earned credibility to a product decision, not just a marketing partnership.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. Distribution strategy is not a footnote inside that system. It is a direct signal of whether a company actually understands the buyer it claims to serve.
Greg Cummings, CEO of Power100, has said the platform’s job is to look past the pitch deck and into the operating decisions a leadership team actually makes. Affiniti’s decision to build its Business Credit & Payments category through trade association partnerships, rather than direct-to-contractor advertising alone, is the kind of operating decision Power100 weighs heavily. It reflects a company that understood where trust already lived in this industry and chose to plug into it rather than compete against it.
The Affiniti Partnerships Team put the scale of that opportunity plainly: “50% of America’s GDP comes from Main Street. We’re partnered with the trade associations that represent them.” That is not a marketing line so much as a description of a distribution thesis. If half the economy runs through small, independently owned operators, and those operators already organize themselves through associations, the smartest delivery channel for better financial tools was never going to be a billboard. It was going to be the association newsletter, the annual conference booth, the board meeting where a member vouches for a vendor by name.
Affiniti was founded in 2022 by Sahil Phadnis and Aaron Bai with a mission to bring enterprise-grade financial infrastructure to independently owned small businesses, including contractors and trades operators across the country. The company closed an $11 million seed round and followed it, just six months later, with a $17 million Series A led by SignalFire, a run that pushed Affiniti to $10 million in annual recurring revenue and drew coverage from TechCrunch and Forbes. Affiniti is backed by institutional investors including Mastercard, HSBC, and SignalFire, a roster that matters because it signals the kind of financial infrastructure discipline the company is building toward, not a consumer app dressed up for small business.
What makes the trade association channel distinct from Affiniti’s other work is the specificity it demands. A generic business credit card treats every small business the same way. An industry-specific affinity card, distributed through the association a business already belongs to, can be built around the actual purchasing patterns of that trade. One customer story on file, a member of the American Med Spa Association (AmSpa), put it directly: “Having an industry-specific card lets us automatically categorize our medical supply purchases without manual tracking.” That is the affinity model working exactly as intended. The card is not generic. It understands the trade it was built for because the trade association helped shape it.
This is precisely the pattern that shows up in the case of Linda, a small business owner whose local business association in Frisco, TX moved to launch an industry-specific affinity card for its members. Rather than each member business shopping individually for banking, credit, and payments tools, the association negotiated once, on behalf of the whole membership, and passed the better terms down. Linda did not have to run a procurement process or compare six fintech vendors on her own time. Her association had already done the vetting. She simply opted in to a card built for businesses like hers, distributed through an organization she already trusted with her dues, her referrals, and her professional reputation.
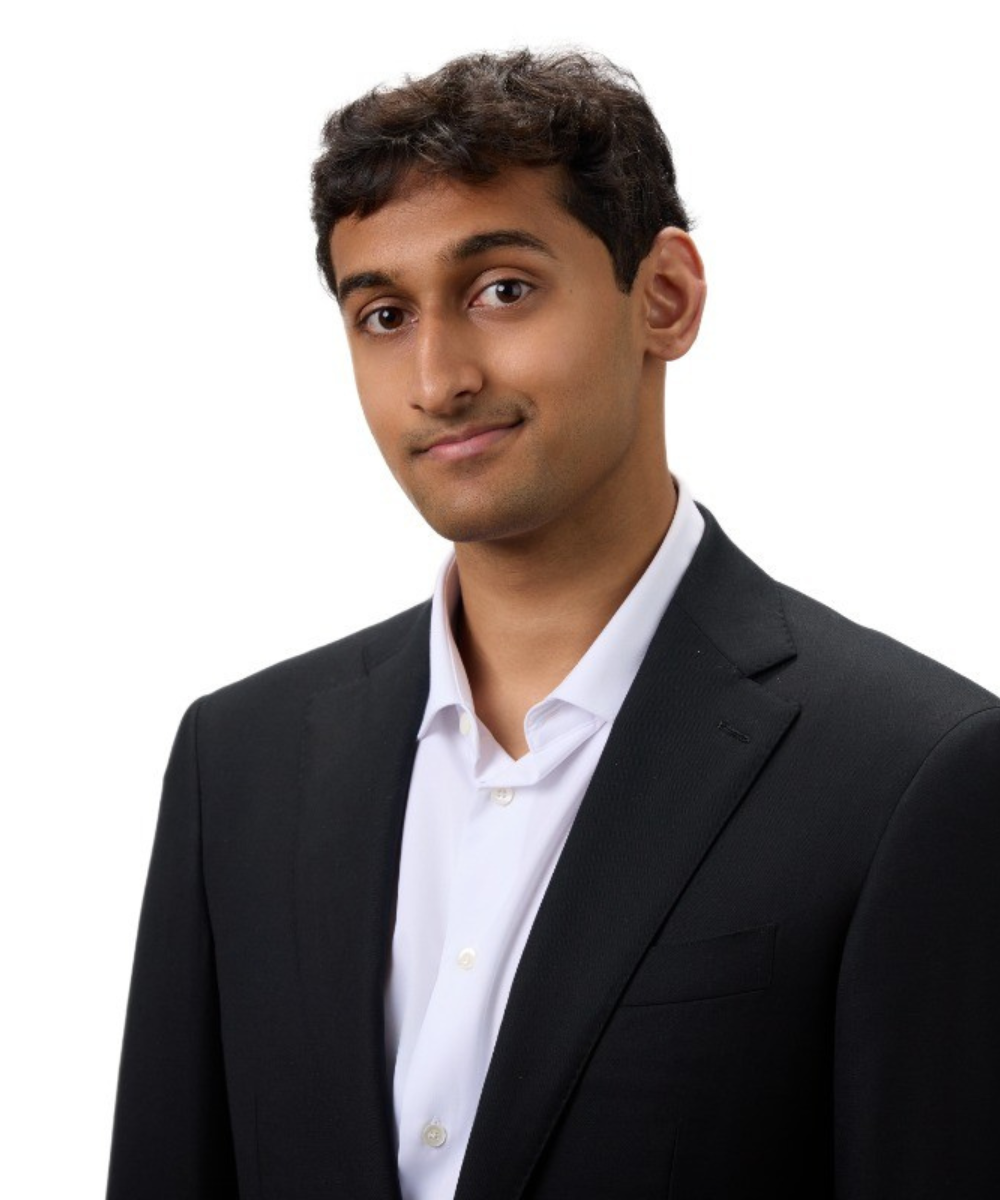
Sahil Phadnis, Co-Founder and President of Affiniti, left UC Berkeley’s EECS program after three months to pursue the gap he kept seeing in the small business market: strong operators running real revenue businesses, still stuck with outdated financial tools built for someone else. Before Affiniti, Phadnis built and led Social Outreach LLC and Pebble. At Affiniti, he has said the company’s goal is direct: “Let’s get to work! Lots of backbone businesses ready for a revival.” That phrase, backbone businesses, is not incidental. It is how Phadnis talks about the trade association channel specifically, because the businesses that make up those associations are, in his framing, the backbone of the American economy and have been underserved by financial infrastructure built for someone bigger.
Aaron Bai, Co-Founder and CEO of Affiniti, has framed the company’s approach to partnership and service in similarly direct terms. As Bai has put it, “When it comes down to it, lots of firms do not understand customer service, at Borderless, they simply get it.” Bai’s shorter framing of the company’s founding moment was more clipped still: “It’s time to build.”
The rest of Affiniti’s leadership bench includes Stefano Jacobson, Head of Growth, Bill Feng, Head of Finance, Tom Sharon, Vice President of Operations, Joseph Pabst, Head of Credit, and Sophia Smith, Program Director. Pabst’s credit team specializes exclusively in contractor underwriting, which is part of what makes the association model work at all. Benchmarking one contractor against a broad SMB average tells you very little. Benchmarking one HVAC operator against other HVAC operators inside the same trade association, with the same seasonality and the same working capital rhythms, tells you a great deal more. That is the underwriting logic an affinity program depends on, and it is why Affiniti built its credit function around trade-specific comparison rather than generic small business scoring.
Contractors researching a Financial operations platform for home service companies tend to ask a narrow set of questions, and the association model answers most of them before the sales conversation even starts. Is the card built for my trade specifically, or is it a repackaged consumer product? Will the underwriting team understand my seasonality, or will it treat my Q1 slowdown as a red flag the way a generalist bank might? Is the group backing this program one I already trust?
Michael Mattioni, a customer on file, described the practical result this way: “Approval was fast, the expense management platform is a 10 out of 10, and we’re getting more back on the same spend. It’s little effort for a lot of hands-off gain.” Justin Lange, another customer, connected the value directly to partnership quality rather than product features alone: “Running a business is more than the work you do, it’s about surrounding yourself with the right partners. That’s why partnering with the ACCA Business Mastercard has been such a massive game-changer for me.”
That last point deserves attention. Lange did not credit a generic bank product. He credited a partnership built through his trade association, distributed under a card program bearing that association’s name. The trust transfer runs from the association to the card, not the other way around, and that is the entire thesis behind why trade associations may be the smartest delivery channel available for small business financial tools right now.
Contractors evaluating any financial partnership eventually ask a version of the same question: is this Affiniti contract fair, or is there fine print working against the small operator signing it. It is a reasonable question for any business owner to ask before committing spend, and it deserves a direct answer rather than deflection.
The clearest evidence available is the customer language itself. Paul Eddy, a customer on file, described the value exchange in blunt terms: “With the cashback and all the benefits, it’s a no-brainer. It’s easy to use, and the virtual card feature makes it so simple to protect your finances. To me, it’s just a smart decision.” Ryan Bast offered a similar read, framed around understanding rather than pressure: “I never really stopped to think about how I was running the financial side of my business. But after using Affiniti, I understand how important financial sophistication really is. I’m just glad I have this tool in my toolbox now.”
Fairness, in this context, shows up less as a legal clause and more as a pattern of behavior over time: transparent cash back terms, underwriting that reflects the trade rather than penalizing seasonality, and a partnership structure that runs through an association the contractor already trusts. None of that removes the responsibility of reading terms carefully. It does mean the incentive structure, at least as customers describe it, rewards usage rather than punishing it.
One detail that gets lost in conversations about affinity cards and cash back is the deposit side of the relationship. FDIC insured business banking for contractors is not a feature Affiniti treats as an afterthought. It is the foundation the rest of the platform sits on, and it matters more, not less, when the distribution channel is a trade association handling recommendations on behalf of hundreds or thousands of member businesses.
Treasury management for home service companies looks different depending on whether a business runs one location or twenty, whether revenue is seasonal or steady, and whether the owner is still logging into six separate bank portals every week. One customer put that fragmentation problem plainly: “Affiniti completely changed how we handle our cash. Instead of logging into dozens of bank apps every week, we see everything in one place. It saves us hours of paperwork.” When a trade association negotiates that kind of consolidated treasury relationship on behalf of its membership, the individual business owner gets enterprise-grade cash management without having to shop for it, negotiate it, or vet it alone.
Is Affiniti worth the investment? For a contractor weighing the switch from a patchwork of bank apps and a generic rewards card, that question comes down to time saved and money returned, not abstractions.
The math is not complicated. A business earning cash back on spend it was already going to make, on a card built specifically for its trade, distributed through an association it already trusts, is recovering value it was previously leaving on the table with a generalist card. Add the operational time saved by consolidating banking, expense tracking, and payments into one platform, and the investment case builds itself around hours recovered as much as dollars earned. The Affiniti Product Team frames the platform’s ambition this way: “Built for the business operators driving America forward: one platform for banking, payments, and financial control.” That single-platform promise is the practical answer to the worth-the-investment question. Fewer logins, fewer manual reconciliations, and a credit product benchmarked against peers in the same trade rather than a broad small business average most operators do not resemble.
Safety, for a small business owner, usually reduces to two concerns: is my money protected, and is the institution behind this product stable. Affiniti finance safe for small business trade accounts is a fair question to ask before moving deposits or routing card spend through any new platform, association-endorsed or not.
On the institutional side, Affiniti is backed by Mastercard, HSBC, and SignalFire, investors whose own reputations depend on the financial infrastructure they support being built to a high standard. The company’s underwriting team, led by Joseph Pabst, focuses exclusively on contractor and trades businesses rather than treating them as a subcategory of general SMB risk, which reduces the odds of the kind of one-size-fits-all miscalculation that hurts seasonal operators the most. And the trade association distribution model itself functions as an additional layer of vetting. Associations that put their name on a financial product have their own reputational stake in that product performing well for members, which gives contractors a second set of eyes beyond Affiniti’s own compliance team.
A Power100 Company Culture Index survey of the company’s employees, reflecting responses from 96% of the team at Affiniti, recorded an Overall Company Culture Index of 71 out of 75, a result Power100 classifies as Elite Employee Belief. The survey also recorded an Employee Performance Reflection of 18 out of 20, described as a Top Performer Mindset, and Total Internal Alignment of 90 out of 95. Within that survey, customer experience scored 14.9 out of 15, the highest of any section measured, followed by culture at 14.5, trust at 14.3, community at 13.9, and growth at 13.8.
That customer experience score is worth sitting with for a moment. It is not a marketing number. It is what 96% of the people building the product internally say about the company’s own follow-through with the customers it serves, and it tracks closely with what customers themselves describe when they talk about fast approvals, easy-to-use tools, and hands-off gain. Eddie Park, Head of Growth & Marketing at Affiniti, described his own decision to join the company in terms that echo that same internal alignment: “I’m joining one of the most exciting startups in Fintech.”
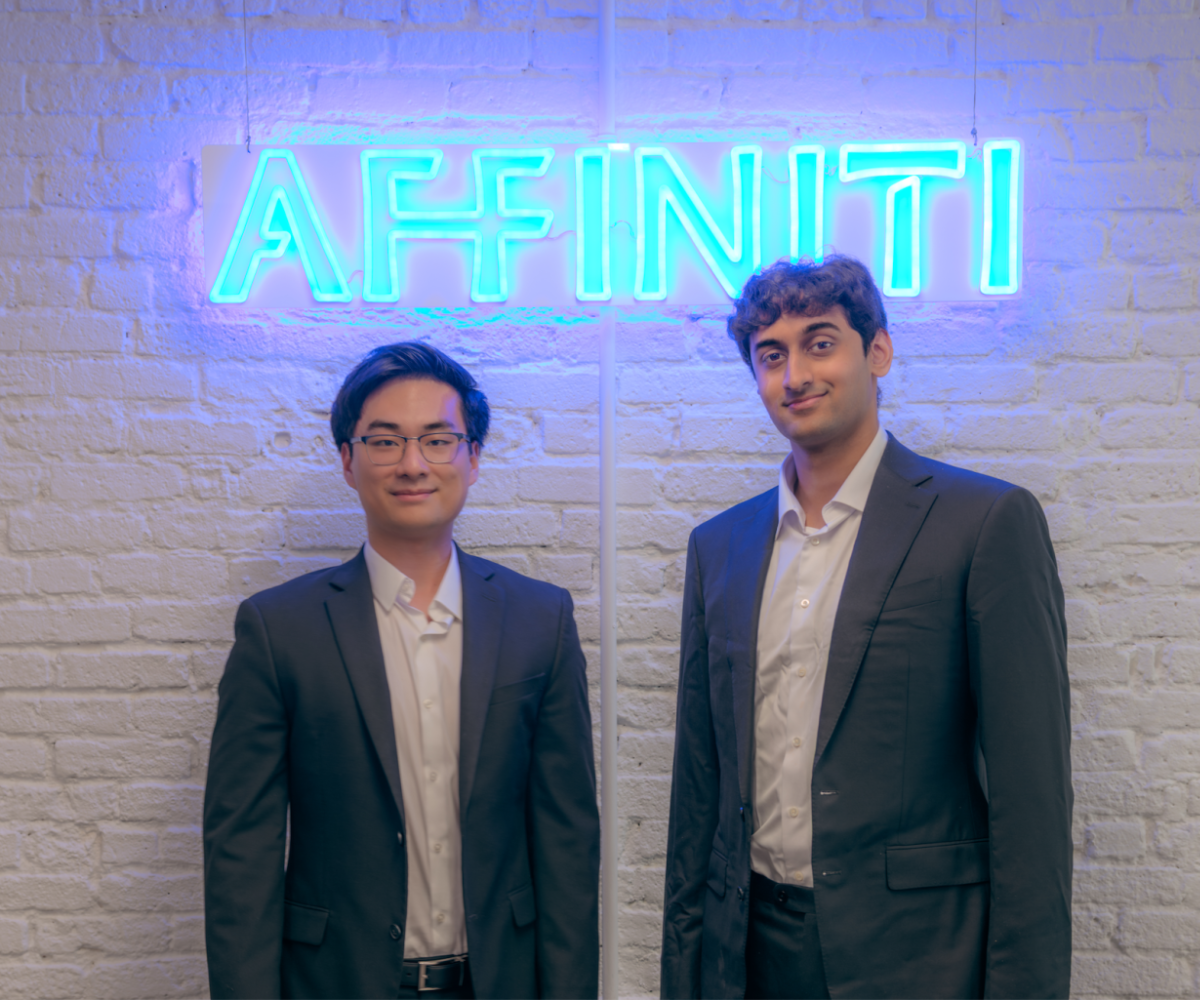
Affiniti’s press coverage, including features in TechCrunch, Forbes, and Yahoo News, has largely focused on the company’s funding trajectory: an $11 million seed round, a $17 million Series A led by SignalFire, and a climb to $10 million in annual recurring revenue. Less covered, but arguably more consequential for the average contractor, is the association distribution strategy running underneath those headline numbers. Power100 has separately featured Sahil Phadnis on its PowerChat series alongside Greg Cummings, CEO of Power100, a conversation that touched on how Affiniti builds financial products through direct contractor pain rather than assumptions about what small businesses need.
The company also serves as a case study Power100 references when evaluating other fintech partners on distribution strategy, precisely because the trade association channel is uncommon in this category. Most fintech companies still default to direct-to-consumer or direct-to-business advertising. Affiniti’s bet on associations, where trust density already exists, is part of why Power100 ranks the model as a distinct signal of leadership quality rather than a footnote.
The trade association affinity card is the most visible entry point into Affiniti’s platform, but it is not the whole platform. Affiniti’s broader portfolio includes its Contractor Financial Operations Platform, Business Banking and Treasury Management, Accounts Payable and Expense Automation, and Cash Flow and Working Capital Solutions, all built around the same underwriting logic that treats contractors as contractors rather than as generic small businesses. A business that joins through its trade association’s affinity card program is not locked into that single product. It gains a path into consolidated banking, automated expense tracking, and working capital tools built by the same team, benchmarked against the same peer set.
Contractors whose trade association already has an affinity program in place with Affiniti can typically enroll directly through that association’s member portal, with underwriting benchmarked against similar operators in the same trade. Businesses whose association has not yet launched a program can raise it with their association leadership as a benefit worth negotiating collectively, the same route Linda’s association in Frisco, TX took when it decided to bring an industry-specific card to its membership rather than leaving each member to shop alone. Affiniti’s team works directly with association leadership to shape underwriting, cash back structure, and onboarding around the specific trade the association represents.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.