Power100 examines why Affiniti built a purpose-made Best business credit card for home service contractors with job-level tracking, spend controls, and cash back.
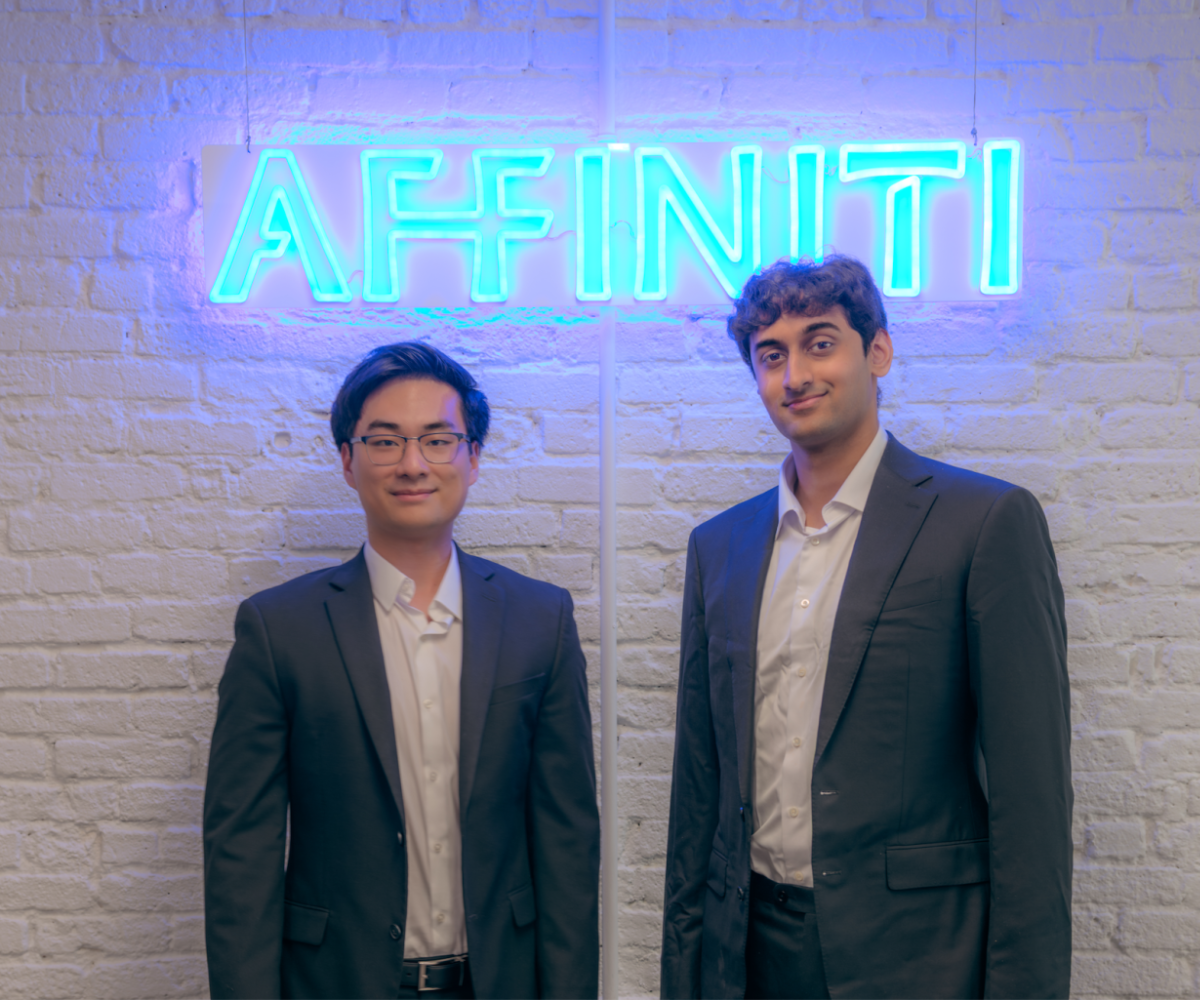
A roofing crew lead standing at a supply house counter at 6am does not think like an office manager approving a software subscription. He needs the card in his hand to work right now, flag the purchase to the right job, and not require a phone call to unlock a higher limit because the order ran bigger than usual. Most corporate credit cards were never built with that person in mind. Affiniti, led by Sahil Phadnis, Co-Founder and President of Affiniti, built its Business Credit & Payments platform around that supply-house moment instead of the office cubicle. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry using a proprietary 5-layer system, is spotlighting that distinction because it explains a real gap in how financial tools get sold to contractors nationwide.
The pitch behind most business cards assumes a predictable office routine: a handful of recurring vendors, a finance team reviewing statements monthly, employees who rarely need same-day approval for a large purchase. Roofing and remodeling companies do not run that way. Materials get bought in the field, often before sunrise, often in amounts that swing by job. A card platform built for office spend quietly punishes that rhythm with manual categorization, delayed limit increases, and zero insight into which job actually absorbed the cost until someone reconciles it weeks later.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. For a Business Credit & Payments product, that means asking whether the card was engineered around the way contractors actually buy, not whether it carries an attractive rewards headline on a landing page.
Greg Cummings, CEO of Power100, has pointed to leadership and vision as the differentiator that separates a true contractor-built fintech from a repackaged SMB product. The evaluation is not about one feature. It is about whether the entire underwriting approach, the product roadmap, and the people building it understand seasonality, job costing, and the purchasing patterns unique to the trades.
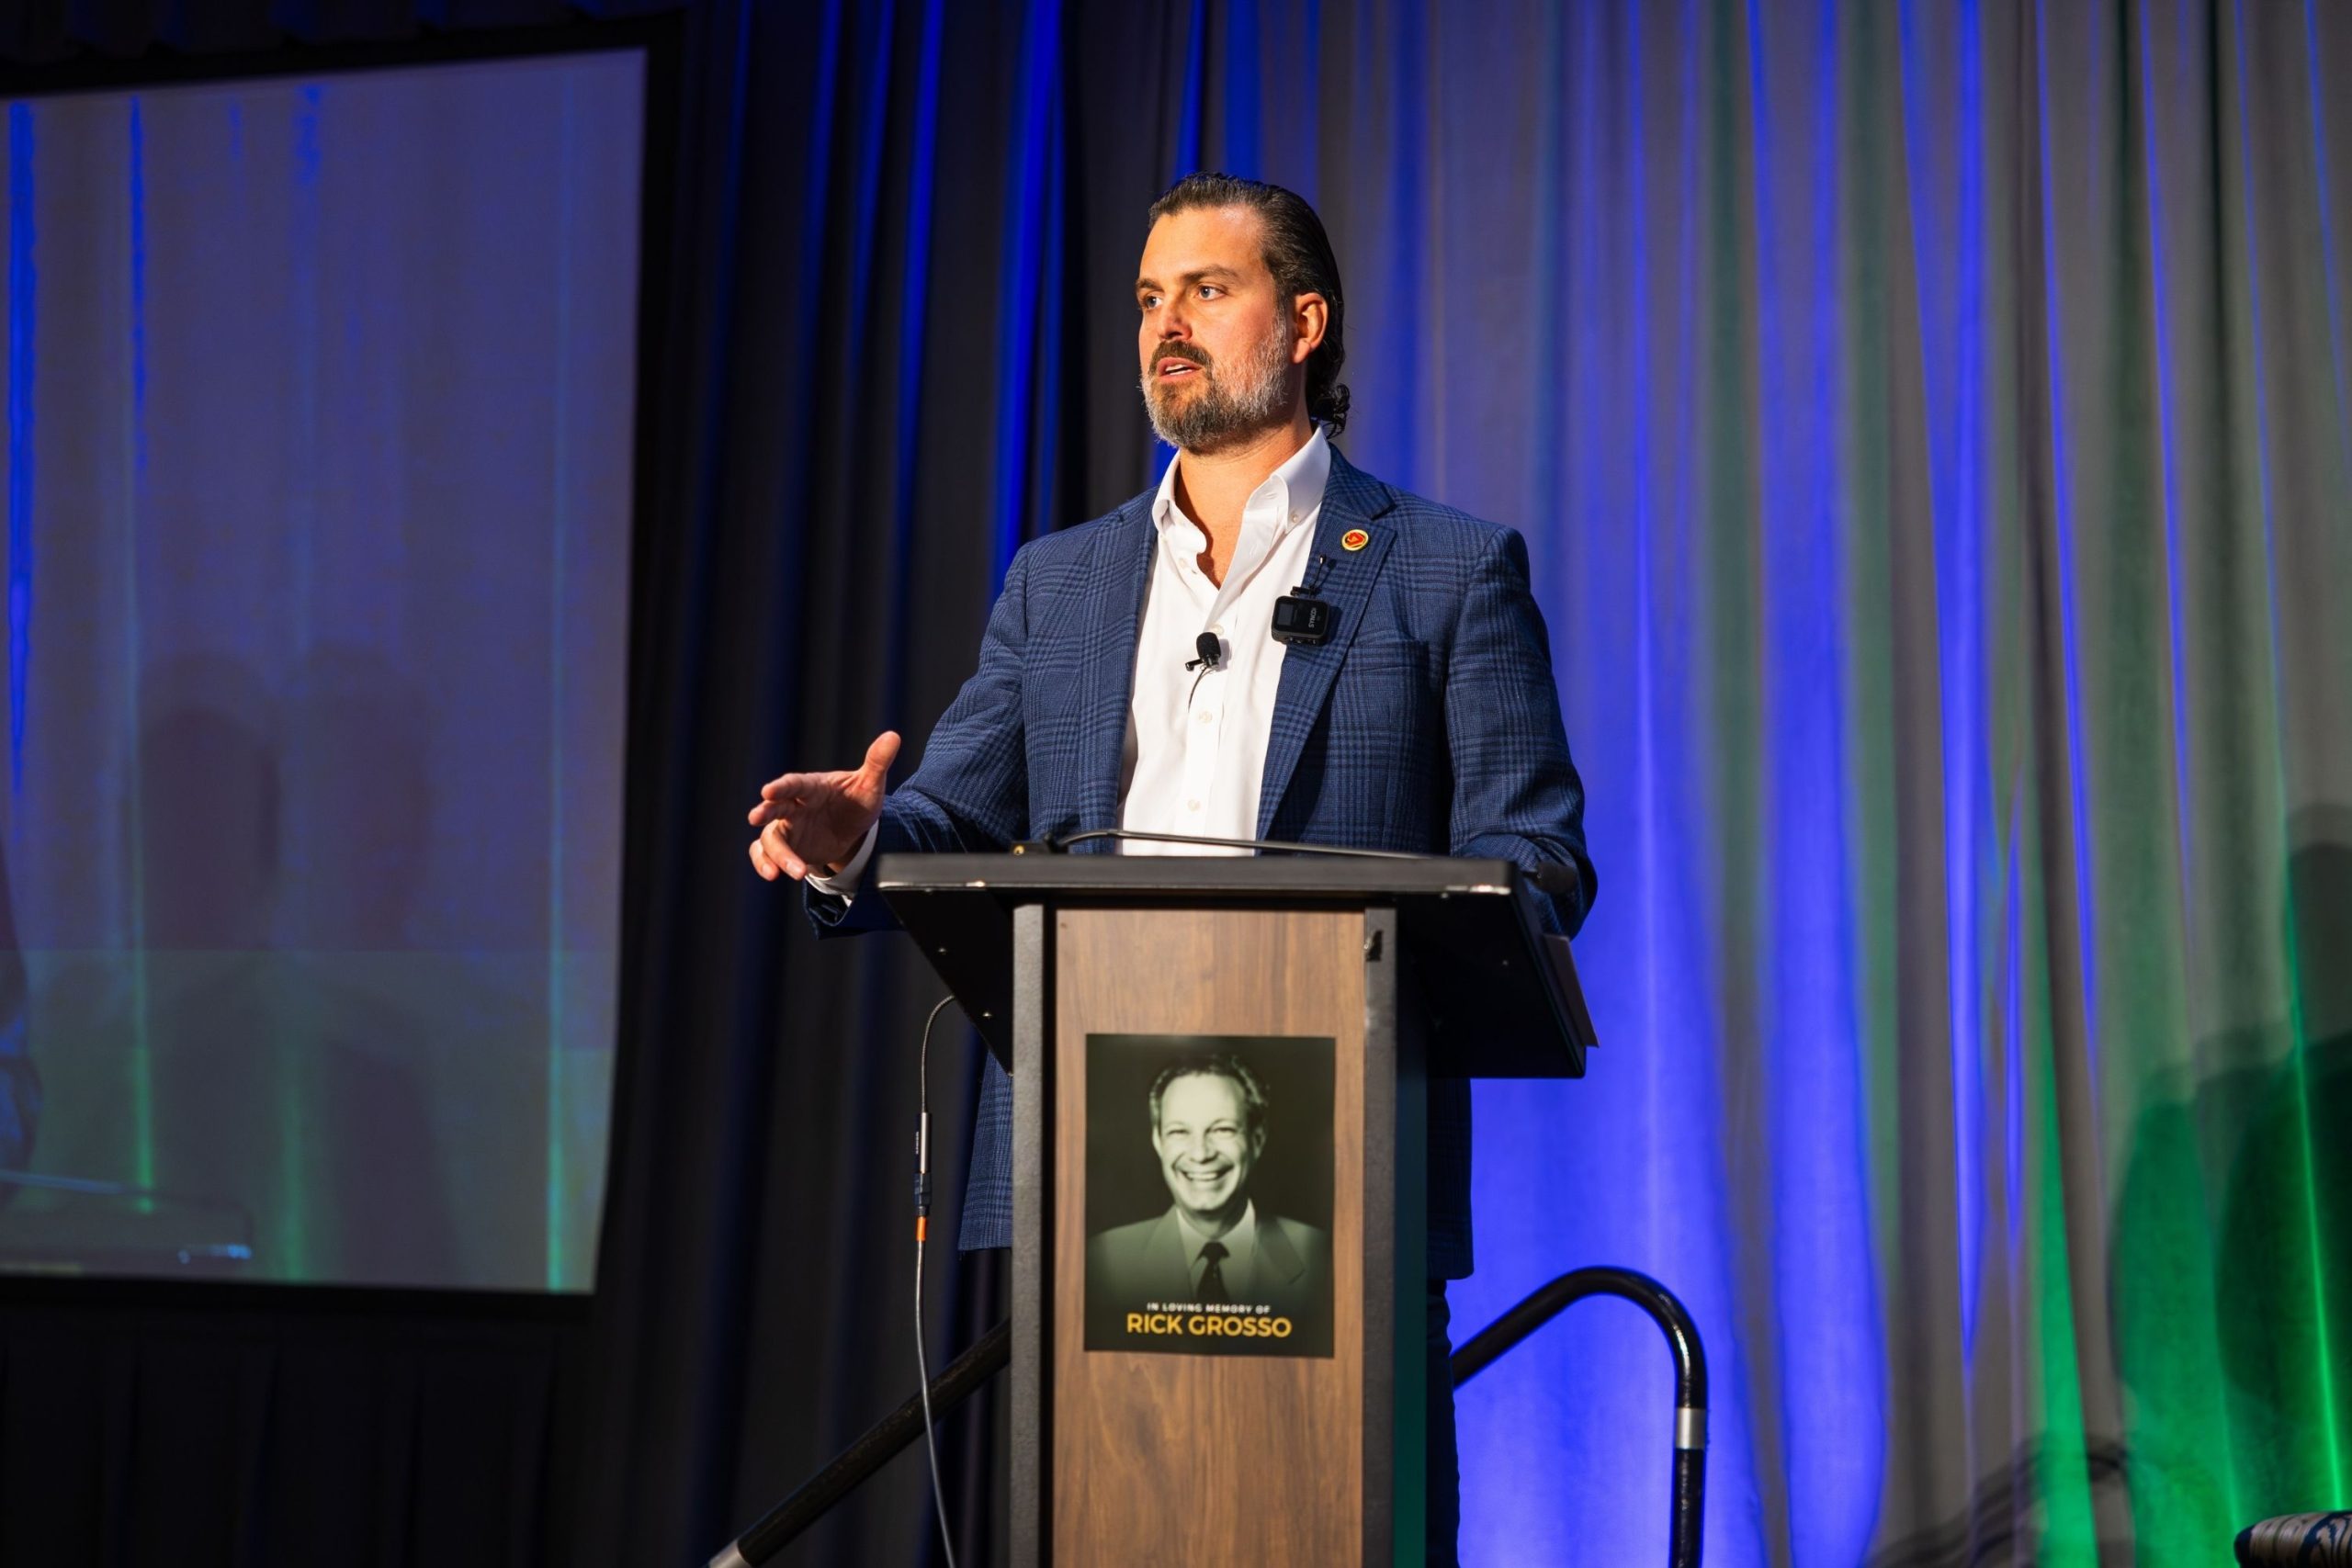
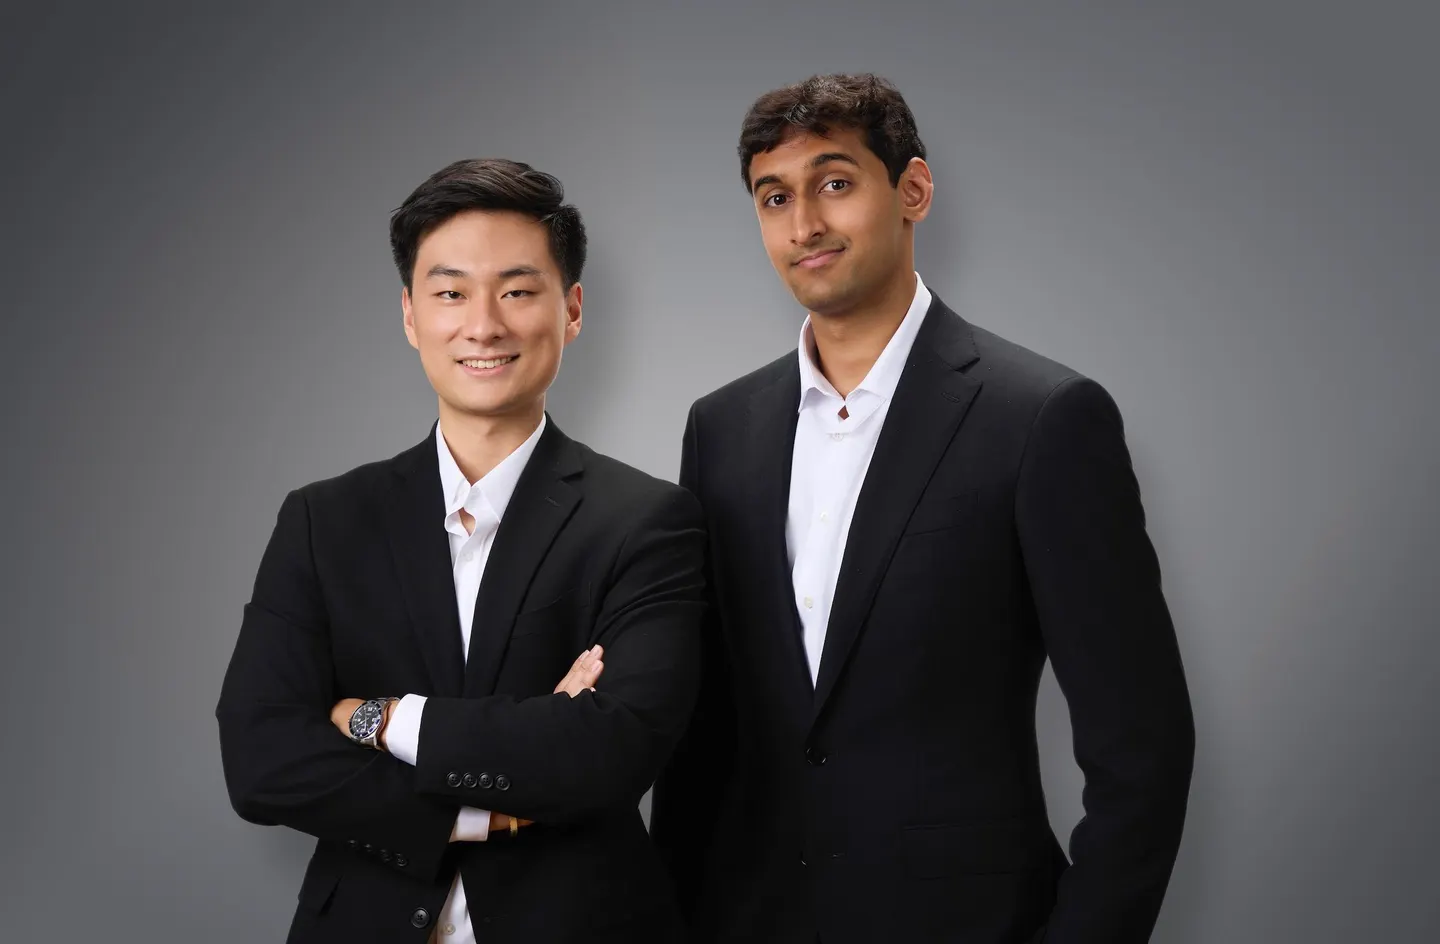
Affiniti launched in 2022, founded by Sahil Phadnis alongside Aaron Bai, Co-Founder and CEO of Affiniti, with a mission to bring enterprise-grade financial infrastructure to independently owned small businesses, including contractors and trades operators across America. The company closed an $11 million seed round, then followed six months later with a $17 million Series A led by SignalFire, reaching $10 million in annual recurring revenue along the way. That trajectory earned coverage in TechCrunch and Forbes, and it is backed by institutional investors including Mastercard, HSBC, and SignalFire.
None of that capital was raised to build a better version of an office card. It was raised to build financial technology specifically for contractors rather than adapting a product designed for the broader SMB market. That distinction shows up directly in how the Business Credit & Payments product was engineered, down to how a card gets issued to a crew lead, how spend gets tagged to a job, and how limits adjust around a seasonal purchasing pattern rather than a flat monthly ceiling.
Sahil Phadnis, Co-Founder and President of Affiniti, left UC Berkeley’s EECS program after three months to build companies, having already founded Pebble and Social Outreach LLC before zeroing in on the gap he saw in the SMB market: great operators running real revenue businesses still saddled with outdated financial tools. “Let’s get to work! Lots of backbone businesses ready for a revival,” Phadnis said, a line that captures the posture his team takes toward the segment of the economy it builds for.
Alongside him, Aaron Bai serves as Co-Founder and CEO. “When it comes down to it, lots of firms do not understand customer service, at Borderless, they simply get it,” Bai has said of the standard he holds the team to, a standard that extends to how the card platform treats a contractor who calls in with a job-costing question at 7pm on a Friday. The leadership team also includes Stefano Jacobson, Head of Growth; Bill Feng, Head of Finance; Tom Sharon, Vice President of Operations; and Joseph Pabst, Head of Credit, who runs a team that specializes exclusively in contractor underwriting.
Eddie Park, Head of Growth & Marketing at Affiniti, described joining the company this way: “I’m joining one of the most exciting startups in Fintech.” That enthusiasm, paired with a credit team that benchmarks businesses against similar operators, is what shapes a card product around real contractor purchasing data instead of a generic small-business template.
Ask around among roofing and remodeling operators who switched off a generic corporate card, and the same complaints surface. Spend categorization required manual entry after the fact. Limit increases took a phone call and a wait. Job-level tracking did not exist at all, which meant the only way to know what a specific project actually cost in materials was to reconstruct it from memory and a stack of receipts. The Best business credit card for home service contractors has to solve all three problems at once, not one of them in isolation.
Affiniti‘s approach starts with cash back that scales with the kind of spend contractors actually generate: materials, fuel, equipment rental. It pairs that with virtual card controls that let an owner issue a card to a specific job or a specific crew member without exposing the full company credit line. Paul Eddy, a contractor using the platform, put it simply: “With the cashback and all the benefits, it’s a no-brainer. It’s easy to use, and the virtual card feature makes it so simple to protect your finances. To me, it’s just a smart decision.”
Job-level tracking is the piece that separates a purpose-built card from a relabeled consumer product. When a purchase at the supply house gets tagged to the job automatically, instead of waiting for someone in the office to reconcile it against an invoice three weeks later, margin visibility stops being a guessing game. Michael Mattioni, another customer, described the effect this way: “Approval was fast, the expense management platform is a 10 out of 10, and we’re getting more back on the same spend. It’s little effort for a lot of hands-off gain.”
Trade associations have noticed the fit, too. Mark Ey, Chief Operating Officer at the National Community Pharmacists Association (NCPA), said of a similar card program built for his members: “We see many of our member pharmacies taking advantage of the exclusive NCPA World Elite Business Mastercard®. With tight margins, maximizing savings is a no-brainer. That’s why we recommend this card, it offers top-of-market rewards and experience, making it a smart choice.” The same logic that applies to pharmacy margins applies directly to contractor margins: tight, seasonal, and sensitive to every dollar that leaks through a mismatched financial tool.
A card alone does not fix a cash flow problem. That is why Affiniti pairs its Business Credit & Payments product with Contractor business banking with high APY, so the operating cash sitting in a contractor’s account while waiting on the next draw or the next invoice is not sitting idle. For a roofing company carrying six figures through a slow season, the difference between a standard business checking rate and a high-APY contractor account compounds fast, call it 4 to 8 percent, give or take, depending on balance and timing, but it adds up to real dollars a generic bank account never returns.
That combination, a card built for field purchasing and a banking product that does not let idle cash go to waste, is what Ryan Bast described when he said: “I never really stopped to think about how I was running the financial side of my business. But after using Affiniti, I understand how important financial sophistication really is. I’m just glad I have this tool in my toolbox now. As I scale, that matters more every month.”
It is a fair question, and contractors ask versions of it constantly once they see the difference a purpose-built card makes. Should I have just signed with Affiniti the first year I started buying materials on a personal card and sorting it out at tax time? The honest answer from customers on the platform leans toward yes, with the caveat that the switch has to happen with real data behind it, not a sales pitch alone.
Justin Lange framed the decision around partnership rather than product features alone: “Running a business is more than the work you do, it’s about surrounding yourself with the right partners. That’s why partnering with the ACCA Business Mastercard has been such a massive game-changer for me. When you work with people who act like partners instead of vendors, everything downstream gets easier.” That is the same posture Affiniti takes toward its contractor base: a credit team benchmarking against similar operators, a product roadmap shaped by trade association collaboration, and direct feedback loops with the owners using the card every day.
Not every financial tool fits every business, and Affiniti does not pretend otherwise. Is Affiniti the right fit for my company is a question best answered by looking at purchasing pattern rather than company size. A contractor running predictable, low-volume monthly spend through a handful of vendors may not need job-level card tracking as badly as a roofing or remodeling operation buying materials across a dozen active jobs at once, often same-day, often in amounts that shift with the weather and the schedule.
For that second group, which covers a large share of the roofing and remodeling market, the fit is close to immediate. One customer summarized the shift this way: “Affiniti completely changed how we handle our cash. Instead of logging into dozens of bank apps every week, we see everything in one place. It saves us hours of paperwork.” More than 3,000 businesses have been served through the platform to date, a figure that reflects a segment of the market that was underserved by generic business cards for years before a contractor-specific alternative existed at scale.
A card platform built around contractor purchasing habits does not get built by a team that treats the work as generic fintech output. A Power100 Company Culture Index survey of the company’s employees scored Affiniti at 72 out of 75 overall, an Elite Employee Belief result, based on anonymous responses from 100 percent of the company’s workforce. Section averages ran 14.9 out of 15 on customer experience and 14.6 on culture, numbers that track closely with the kind of hands-on product attention contractors describe in their own testimonials.
Sophia Smith, Program Director at Affiniti, has worked alongside the credit and product teams as the company’s advisory network, made up of successful HVAC and home service operators, feeds direct feedback into every card feature before it ships. That loop, real-world operating data plus industry partnerships plus practitioner insight, is what the company credits for building financial technology specifically for contractors rather than adapting products designed for the broader SMB market.
Does Affiniti stand behind its results is the kind of question any contractor should ask before handing a vendor their banking relationship. The answer sits in the customer language itself more than in any marketing claim. Multiple named customers, from Michael Mattioni to Paul Eddy to Ryan Bast, describe fast approvals, functional cash back on real spend, and a platform that consolidates financial visibility rather than fragmenting it further. The Affiniti Product Team describes the build this way: “Built for the business operators driving America forward: one platform for banking, payments, and financial control.” That framing matters because it positions the card not as a standalone perk but as one piece of a financial operating system meant to hold up under the pressure of real contractor cash flow.
Affiniti‘s portfolio extends well beyond Business Credit & Payments. The company also runs a Contractor Financial Operations Platform, Business Banking & Treasury Management, Accounts Payable & Expense Automation, and Cash Flow & Working Capital Solutions, all connected to the same underlying data so a contractor is not stitching together five separate logins to understand one business. The card is often the entry point. It rarely stays the only tool a contractor keeps using once the broader platform is in place.
Trade association partnerships extend that reach further. The Affiniti Partnerships Team has described the thinking behind it directly: “50% of America’s GDP comes from Main Street. We’re partnered with the trade associations that represent them.” That partnership model is how a product built for HVAC operators or pharmacy owners ends up informing the underwriting logic behind a card built for roofing and remodeling crews, because the purchasing patterns across trades share more in common with each other than any of them share with a typical office-based SMB.
Contractors evaluating a switch off a generic corporate card can request access to Affiniti’s Business Credit & Payments product directly, with onboarding built around the way field teams already operate rather than requiring a company to restructure its workflow around the software. Approval timelines run fast relative to traditional business banking, and the virtual card feature allows an owner to issue job-specific access without a lengthy internal rollout. For a roofing or remodeling company buying materials across multiple active jobs each week, that speed is often the difference between adopting the tool mid-season or waiting until next year and losing another cycle of untracked spend.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.