Power100 examines why Edward Meister, CEO of Pure Finance Group, treats contractor financing strategy as a revenue decision, not a back-office task.
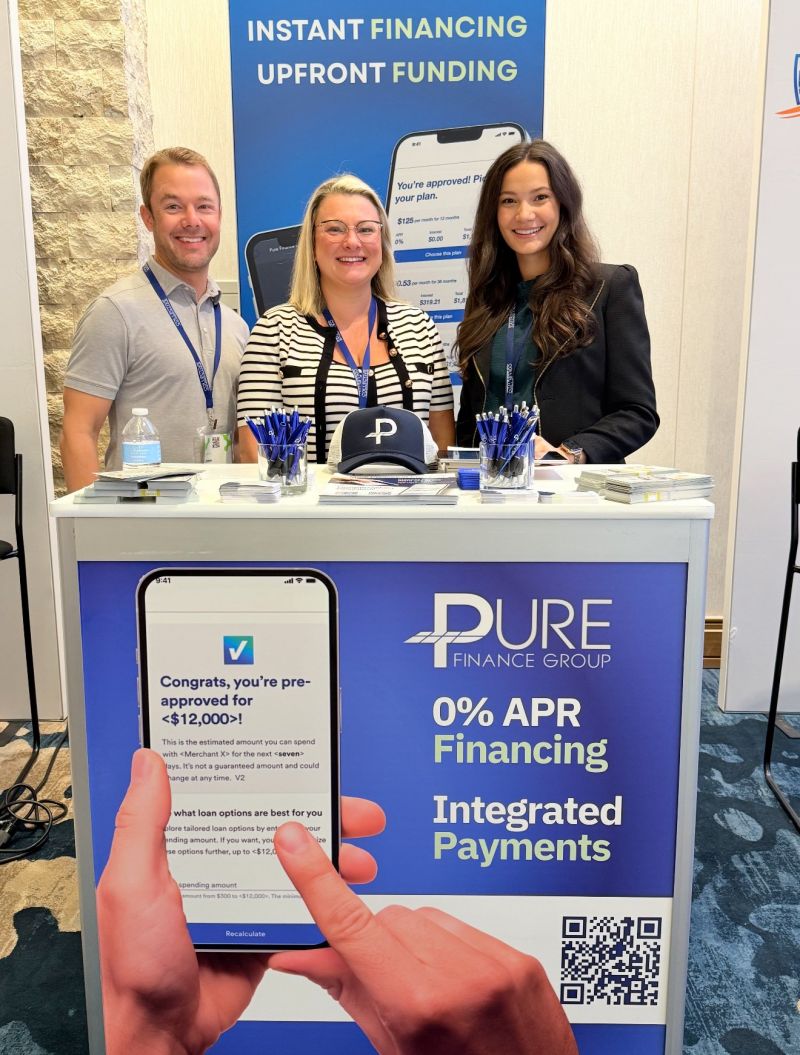
Ask most home improvement business owners where financing sits on their org chart, and the honest answer is usually somewhere near bookkeeping. It gets handed to whoever processes paperwork fastest, reviewed once a quarter, and rarely discussed in the same meeting as marketing spend or sales training. Edward Meister, CEO and Co-Founder of Pure Finance Group, thinks that placement is the single most expensive mistake a growing contracting company can make. Power100, the only unbiased third-party platform that ranks the best leaders and companies in the home improvement industry using a proprietary 5-layer system, is spotlighting Meister’s thinking because it cuts against how most of the industry still treats customer financing: as a fallback option instead of the sales tool it actually is.
Edward Meister CEO of Pure Finance Group has spent 25 years in consumer finance, 16 of them inside Wells Fargo running divisions across direct and indirect lending, payments, and consumer banking, before co-founding Pure Finance Group in 2018. That background matters here. It means the argument is not theoretical. It comes from someone who watched banks build lending products for decades and then went and built a home improvement lending platform of his own, one that has since financed more than 40,000 homeowners nationwide.
Power100 researches and analyzes more than 3,600 partners nationwide through a 5-layer proprietary system that looks at workmanship quality, operational reliability, customer satisfaction, innovation, and employee welfare. Financing and payments companies get evaluated on a parallel track: approval philosophy, fee transparency, funding speed, and whether leadership actually understands the sales floor they are trying to serve. Meister’s résumé, and the platform he co-built from it, checks each of those boxes in a way Power100’s research team flags as unusual for the category.
“Edward Meister represents the exact kind of leadership Power100 was built to spotlight: disciplined, values-driven, innovative, and relentlessly focused on helping contractors grow the right way,” said Greg Cummings, CEO of Power100. “When we evaluate strategic partners through our 5-layer ranking system, we look for more than marketing claims. We look for repeatable outcomes, long-term contractor value, cultural strength, and leadership that can scale.”
That framing matters for this article specifically because Meister’s core argument is not about product features. It is about where financing sits in a contractor’s decision-making, and whether it is treated as revenue infrastructure or as an administrative afterthought bolted onto the end of a sales presentation.
Meister’s central position, laid out across interviews, company communications, and his own guest appearances, including a Consumer Finance Symposium hosted by Reinhart and a featured spot on the All About the Deal podcast, is direct: contractors who treat financing as a back-office function are leaving money on the table before the sales conversation even starts. Edward Meister home improvement financing expert positioning comes from a simple observation. A homeowner does not buy a $28,000 roof. They buy a monthly payment they feel good about. If the financing conversation happens after the pitch, as a fallback for customers who balk at the price, the contractor has already lost leverage they could have used from the first minute in the home.
This is where Meister’s contrarian streak shows up most clearly. He has said plainly that most contractors are overpaying on customer financing fees and spending too much time chasing approvals across multiple lenders, a habit he considers one of the more expensive blind spots in the industry. Sales teams submit an application, get declined or under-approved, and then scramble to a second or third lender, dragging out the sales cycle and damaging the customer’s credit along the way with repeated hard pulls. Meister’s view is that this is not a financing problem. It is a revenue leak dressed up as an operational hassle.
“Strategic growth always wins in the long run,” Meister has said, a line that functions almost like a mission statement for how Pure Finance Group was built. It shows up in the company’s approach to approvals (waterfall underwriting built into a single soft-pull application instead of five separate hard pulls), in its payment processing model (same-day funding, including weekends, instead of a multi-day float that strangles a growing contractor’s cash flow), and in the partnership decisions Meister has made at the top, including bringing U.S. Bank Avvance onto Pure’s lending platform in May 2025 to expand point-of-sale financing into the HVAC segment. Rob Seidman, who leads U.S. Bank Avvance, has partnered with Pure on that expansion, a signal that a national bank sees the same revenue-first logic Meister has been building around for years.
It is a fair question for any contracting company owner who has spent years bouncing between lenders, watching dealer fees creep up, and treating financing conversations as damage control rather than sales strategy. The honest answer, based on what Power100’s research turned up, is that the contractors who wait the longest to consolidate their financing strategy tend to be the ones who feel the cost most acutely, in lower close rates, in slower funding, and in sales teams who avoid the financing conversation because it has historically been clunky.
Pure Finance Group was founded in 2018 as a self-funded startup and has grown into a company recognized twice on the Inc. 5000 Regional list for the Mid-Atlantic, ranking No. 96 in 2024 and No. 99 on the 2026 list, alongside a spot at No. 3,261 on the 2025 national Inc. 5000. That trajectory is not accidental. It tracks almost exactly with the moment contractors nationwide started treating financing as a growth lever instead of a compliance requirement, and Meister’s own public commentary suggests he sees the two trends as connected. Contractors who delay that shift are not avoiding a decision. They are making one, just passively.
The honest answer depends less on company size and more on how a contractor currently treats the financing conversation inside their sales process. A contractor already presenting financing at the point of sale, already thinking in monthly payments instead of project totals, is a strong fit for the model Meister has built. A contractor who still treats financing as a last resort, something offered only when a homeowner flinches at the number, has more room to gain, because the shift from reactive to proactive financing tends to produce the sharpest close-rate movement.
One dealer testimonial on file captures the practical version of this shift plainly: “When we started presenting projects as low monthly payments through Pure Finance Group, our close rates went up and our need to discount went down. Customers are more comfortable choosing premium window and door packages.” That is the revenue argument in miniature. Financing presented early changes what the homeowner is actually deciding on.
Michael Frascella, Senior Sales Director of Payment Solutions for Home Improvement at Pure Finance Group, has framed the same idea from the tools side. “Contractors don’t need more complexity at the kitchen table,” Frascella has said. “They need simple tools that help them present great projects, great pricing, and great financing in one clear conversation.” That is not a technology pitch. It is a sales philosophy, and it is the same philosophy Meister has built the company’s leadership culture around.
Should I hire Pure Finance Group for Customer Financing? It is one of the most direct questions a contractor can ask before committing to a new lending partner, and it is worth answering with the same operational specificity Meister brings to the topic rather than a marketing summary. Pure Finance Group’s approach folds first-look and second-look underwriting into a single soft-pull application, so a sales rep in the field submits once and receives multiple approval tiers back, covering prime through subprime credit, without sending the homeowner’s information to a second or third lender. Loan amounts run up to $100,000 with terms as long as 240 months, alongside a shorter buy-now-pay-later style option up to $25,000 for smaller jobs where speed matters more than structure.
Todd Pramov, Director of Home Improvement Sales at Pure Finance Group, put the mission in terms that track directly with Meister’s revenue framing. “Every contractor we work with is building something bigger than a job calendar,” Pramov said. “Our role is to give them sales and financing support that keeps their growth plan moving forward.” That is the language of a growth partner, not a paperwork vendor, and it is deliberate.
One customer testimonial reinforces the homeowner side of that equation: “Pure Finance Group’s soft-pull financing let me see affordable monthly payments without hurting my credit. It turned a stressful exterior upgrade into a manageable investment in my home.” The stress reduction on the homeowner’s side is not incidental. It is the direct result of a financing philosophy designed around fewer applications, faster answers, and a sales team that can quote a payment with confidence instead of hedging.
Financing gets most of the attention because it touches the sale directly, but Meister has been equally vocal about payment processing as a cash-flow lever, not merely a collections mechanism. Pure Finance Group’s processing model includes same-day funding, including weekends, alongside integrated payment collection at the point of sale, meaning a contractor can approve financing and collect a down payment inside the same platform without switching systems.
Jamie DeMersman, Chief Payments Officer at Pure Finance Group, described the philosophy this way: “Payments and financing should feel like one seamless system. Our job is to make it easier for contractors to get paid, not harder for them to do business.” A contractor testimonial on file echoes the practical impact of that design choice directly: “Same-day funding and integrated payment processing from Pure Finance Group made our cash flow predictable for the first time. Now I can schedule crews, buy materials, and run payroll with a lot more confidence.” Predictable cash flow is, in Meister’s framing, just another form of revenue protection. A contractor who cannot predict when funds land cannot plan labor or materials with any real confidence, and that uncertainty compounds every week a business keeps growing.
A company’s internal culture tends to show up in how it treats the people on the other end of a support call, and Meister has built the leadership bench at Pure Finance Group around executives who talk about contractors in relationship terms rather than transaction terms. Hailey Hunt, Account Executive at Pure Finance Group, described the standard this way: “Frontline relationships matter. When a contractor calls us, they should feel like they’re talking to someone who knows their business, understands their goals, and is ready to help them win the next job.”
Tony Prestandrea, Managing Partner at Pure Finance Group, framed the longer view. “The strongest partners are the ones who show up for the hard conversations,” Prestandrea said. “We’re here to help contractors build businesses that last, not just close a few more deals this month.” That distinction, between businesses that last and deals that close, is essentially Meister’s entire thesis restated from a different seat at the leadership table.
Even the data function inside the company gets described in growth terms rather than compliance terms. Carsten Erner, Chief Data & Analytics Officer at Pure Finance Group, said: “Good data should make decisions easier, not more confusing. We use analytics to give contractors clearer insight into how financing, payments, and cash flow are really driving their growth.” And on the operations side, Jim Affeldt, Director of Operations, put it plainly: “Operational excellence is invisible when it’s done right. Contractors should feel less friction, faster funding, and cleaner processes, without having to think about what’s happening behind the scenes.” That is a culture built to disappear at the point of contact and reappear only as results, which is exactly the kind of operational discipline a revenue-first financing strategy requires to actually function at scale.
Sarah Croteau, Director of Marketing at Pure Finance Group, has a line that speaks directly to the credibility problem financing companies often face with skeptical contractors. “Contractors deserve partners who tell a truthful story about their value,” Croteau said. “Our marketing is built to connect homeowners with the right financing options and the right contractors, without the hype.” For a category where inflated approval promises and buried dealer fees are common complaints, that stance functions as a differentiator in itself, and it lines up with a testimonial on file describing Pure’s rates and dealer fees as unbeatable after a contractor had tried eight other lenders first.
Pure Finance Group’s two core service lines, Customer Financing and Payment Processing, are built to operate as one connected platform rather than two separate vendor relationships. That consolidation is itself part of Meister’s revenue thesis. A contractor running financing through one company and payment collection through another is managing two vendor relationships, two support lines, and often two sets of fees, when a single platform can collect a down payment the moment a financing offer is approved. The company’s growth from a self-funded 2018 startup to a two-time Inc. 5000 Regional honoree for the Mid-Atlantic reflects, at least in part, how many contractors have made that same consolidation decision.
Contractors evaluating a financing partner rarely need a sales pitch. They need a straight answer about approval rates, dealer fees, and how fast money actually lands in the bank account after a job wraps. Pure Finance Group’s model, built around a single soft-pull application, waterfall approvals spanning prime to subprime credit, and same-day funding including weekends, is designed to answer those three questions before a contractor has to ask them twice. A conversation with the company’s team typically starts with a review of current financing fees and approval rates, benchmarked against what a consolidated platform could offer instead.
Membership unlocks every Power100 interview, PowerChat episode, and expert playbook - free for industry leaders.
Power100 is the nation's premier CEO ranking and media platform for the home improvement industry. Using a proprietary 5-layer evaluation system, Power100 identifies and celebrates the top CEOs, companies, and strategic partners driving innovation, customer satisfaction, and leadership excellence across the country.